Category Archives: Case Studies

convenience store beverages

Florida Convenience Store Purchase

Our Florida-based clients just purchased another convenience store, adding to their portfolio.

Convenience store financing is still a very doable proposition, particularly if the sale of the business includes commercial real estate.

Senior Associate Ryan Dumas was pleased with the closing. Ryan said, “My clients have a strong partnership and very good business practices. They understand what’s needed to run a successful convenience store from inventory to staffing. And they also know the local marketplace very well with another C-store in the same metro area.”

Some deal details: The loan closed with no money down. The lenders were satisfied with the current business and required minimal documentation. There was one roadblock: the appraisal was a little lower than expected. But that did not prevent the closing. If you have a local or national asset, we encourage you to contact Ryan.

What to Consider in Purchasing a Convenience Store

  • Location: Where are your nearest competitors and what do they offer?
  • How will you differentiate yourself in the marketplace? Do you need to consider upgrading signage or inventory? If you don’t sell gas, how will you compete with stores that do?
  • Will the store operate as a franchise or be independent? What are the benefits and drawbacks of each of these decisions?
  • Will you retain current employees or hire new ones? How stable is the local employment pool?
  • How hands-on will you have to be as an owner/operator, especially during the first year of ownership? Are you prepared to be onsite regularly if necessary?
  • Crunch the numbers: How profitable has this store been before? Calculate the COGS (cost of goods sold). Compare the COGS to other nearby properties.
  • Do you have a general idea of the value of the commercial real estate? Determine if the purchase price seems realistic.
  • What will you do differently in the future to enhance revenue and keep expenses down?
  • If you aren’t already, be sure that you receive monthly financial statements including balance sheets from the current owners.
  • Know your business: its statistics, its regular payrolls costs, anticipated insurance premiums, and other regular and occasional expenses.
  • Is there upcoming deferred maintenance that will become your responsibility? How will you pay for them?
  • Hire an attorney. This is a very big step and you will be spending money and have financial responsibilities. An experienced commercial real estate attorney protects you from typical roadblocks.

Why Choose GRP Capital?

Our GRP Capital team specializes in crafting financing solutions tailored to each client’s unique goals. We even have experience with lender dropouts and critically timed funding needs.

Whether you’re purchasing, refinancing, or building from the ground up, our extensive network of lenders ensures you’ll find funding that aligns with your goals and cash flow needs.

Here’s what sets us apart:

  • We save you time by researching and identifying the best funding options for your project.
  • Our expertise spans various loan products—including non-recourse loans, SBA loans, bridge loans, and conventional financing—so you can navigate even the most complex transactions confidently.
  • Beyond lending, we provide strategic guidance on operational decisions that drive long-term business success.
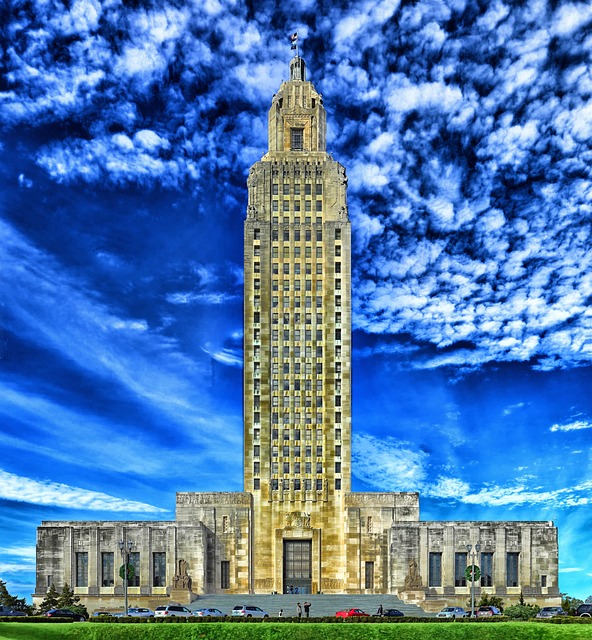
Louisiana Baton Rouge hotel

Louisiana Hotel Operator Bought Hotel

Congratulations to our Louisiana client, who purchased his first hotel.

Sometimes the way into business ownership is to first work in the business. Our client had been operating and leasing a hotel, with an eye to eventually owning

The client showed fortitude through the ups and downs of the Louisiana hospitality marketplace. The larger Louisiana hotel industry has had some soft spots. Even this hotel has not been as profitable as before, but is outperforming in this specific marketplace.

Senior Associate Ryan Dumas worked very hard with this client as he encountered some challenges. Ryan said, “My team and I gave a lot of time and attention to this first-time buyer. I personally collaborated with him to prepare for the appraisal and lender site visits. It was really important for him to feel confident in being able to express his business plan and vision for the process. We also worked closely with the client’s attorney to help deal with title issues and revising operating agreements and filings.”

Tips for First Time Business Owners

  • Spend time on an accurate and complete management resume, which highlights your skills.
  • Work on a three year business plan, considering expected revenues and expenses.
  • Monitor your own personal cash flow and build up your savings.
  • You will have to prove your ability to use the business profits to pay for the new mortgage. Be sure you have adequate debt coverage. GRP Capital can review your financial statements, focusing on debt coverage.
  • If you aren’t already, be sure that you receive monthly financial statements including balance sheets from the current owners.
  • Know your business: its statistics, its regular payrolls costs, anticipated insurance premiums, and other regular and occasional expenses.
  • Are there upcoming deferred maintenance that will become your responsibility? How will you pay for them?
  • Hire an attorney. This is a very big step and you will be spending money and have financial responsibilities. An experienced commercial real estate attorney protects you from typical roadblocks.

Why Choose GRP Capital?

Our GRP Capital team specializes in crafting financing solutions tailored to each client’s unique goals. We even have experience with lender dropouts and critically timed funding needs.

Whether you’re purchasing, refinancing, or building from the ground up, our extensive network of lenders ensures you’ll find funding that aligns with your goals and cash flow needs.

Here’s what sets us apart:

  • We save you time by researching and identifying the best funding options for your project.
  • Our expertise spans various loan products—including non-recourse loans, SBA loans, bridge loans, and conventional financing—so you can navigate even the most complex transactions confidently.
  • Beyond lending, we provide strategic guidance on operational decisions that drive long-term business success.
Pennsylvania farmland

Pennsylvania Hotel Purchased with 504 Loan

Our clients successfully purchased a Pennsylvania hotel loan, using the SBA 504 loan program. They felt that the property had good revenue potential and that they were an ideal set of owner/managers.

Ultimately, GRP Capital matched the clients with a senior lender and a Community Development Corporation. Both of these are needed for a 504 loan. SBA 504 loans are especially attractive right now in the hospitality realm. Conventional lenders can still be hesitant to lend money for hotel businesses, especially outside large metropolitan areas. But the SBA guaranty is enticing to a larger group of lenders. In addition, an SBA 504 loan can be used for slightly more expensive loans

Senior Associate Ryan Dumas really enjoyed working with this partnership group. He stated, “These guys were ideal partners. They are strong, experienced, hands-on operators, who have shown previous success as owner/operators. Most importantly, they were organized, motivated and had a strong business plan. At least one partner knew the area well and was ready to be on-site. This property will benefit from their hands-on, knowledgeable management.”

Advantages of an SBA 504 Loan

  • Lower down payment/equity injection
  • Competitive fixed-rate financing for the life of the loan
  • Long repayment periods (up to 25 years)
  • Affordable payments as a result of the loan repayment periods, which impacts cash flow immediately

Should you consider a 504 loan?

• Are you and all owners of the borrowing entity U.S. Citizens? As of this writing, the SBA regulations require that an applicant for a 504 loan or a 7A loan must consist of 100% citizens. (In the past, a borrowing entity could have a small percentage of permanent residents, that is Green Card holders.)

• Are you current with all previous SBA loans? Each partner of the borrowing entity will have to disclose their current and past SBA loans. Any loans that are not in good standing could delay or prevent the loan from closing. Be particularly mindful of previous EIDL (Economic Injury Disaster Loans). How to find out if you are current with your EIDL loans?

• What’s your timeline? SBA 504 loans can take a little bit longer to close, because two entities are underwriting the loan. If you are considering accessing this type of loan, make sure your Purchase Sale Agreement (PSA) allows enough time to close. Consider engaging an attorney to represent you through this part of the process.

More information about the SBA Debenture Process

Why Choose GRP Capital?

Our GRP Capital team specializes in crafting financing solutions tailored to each client’s unique goals. We even have experience with lender dropouts and critically timed funding needs.

Whether you’re purchasing, refinancing, or building from the ground up, our extensive network of lenders ensures you’ll find funding that aligns with your goals and cash flow needs.

Here’s what sets us apart:

  • We save you time by researching and identifying the best funding options for your project.
  • Our expertise spans various loan products—including non-recourse loans, SBA loans, bridge loans, and conventional financing—so you can navigate even the most complex transactions confidently.
  • Beyond lending, we provide strategic guidance on operational decisions that drive long-term business success.
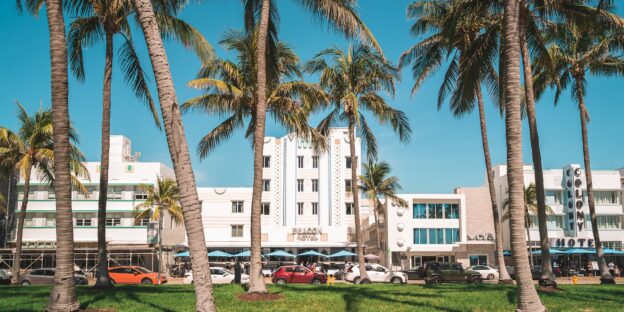
Bridge Financing Closes for Miami Beach Boutique Hotel

Picture a boutique hotel a block from the ocean on Miami Beach, its Art Deco lines catching the South Beach light. Our clients, an experienced investment group and repeat clients of GRP Capital, were ready to add this property to their portfolio, and they wanted to move quickly.

Boutique hotels in premier markets like Miami Beach are prized assets, but they can be tricky to finance. The purchase price reflects the location and the upside, and the ownership was organized as an investment fund, a structure that not every lender wants to underwrite. Speed mattered too. Our clients needed to close on a tight timeline to secure the property.

A bridge loan was the right tool. Bridge financing gave the borrowers the speed and flexibility to acquire the asset now and execute their business plan, with a clear path to permanent financing once the property stabilizes. GRP Capital placed the sub-$10 million loan with a lender who knew the market and could close fast.

Krishan Patel, Managing Director of GRP Capital, stated, “These are sophisticated, repeat clients who know the Miami Beach market well. The property is a special one, and the ownership structure called for a lender comfortable with an investment fund and a boutique asset. We focused on speed and certainty of close, and we placed the loan with a partner who shared that urgency. It is exactly the kind of premium, complex transaction our team is built to handle.”

Bridge loans are powerful, but they are not the right fit for every borrower or every property. Here is what to understand before you use one.

What to Know About Bridge Financing:

• Bridge loans buy time: A bridge loan is short term, typically twelve to twenty-four months, and lets you acquire or reposition now and refinance once the numbers support it.

• Speed is the advantage: Bridge lenders can often move faster than SBA or conventional lenders. When a purchase depends on a tight closing, that speed can be the difference between getting the property and losing it.

• Price reflects flexibility: Bridge rates run higher than SBA or conventional rates. That premium buys speed, flexibility and a structure that fits complex ownership. Build the cost into your business plan and your exit.

• Have an exit in mind: The strongest bridge borrowers know how they will get out, usually a refinance after stabilization. Plan the exit before you take the loan, not after.

Why Choose GRP Capital?

Our GRP Capital team specializes in crafting financing solutions tailored to each client’s unique goals. We even have experience with lender dropouts and critically timed funding needs.

Whether you’re purchasing, refinancing, or building from the ground up, our extensive network of lenders ensures you’ll find funding that aligns with your goals and cash flow needs.

Here’s what sets us apart:

  • We save you time by researching and identifying the best funding options for your project.
  • Our expertise spans various loan products—including non-recourse loans, SBA loans, bridge loans, and conventional financing—so you can navigate even the most complex transactions confidently.
  • Beyond lending, we provide strategic guidance on operational decisions that drive long-term business success.
Pari Passu Financing Closes for a Central Florida Hotel

Our clients set out to buy two Florida hotels at once, both out of a receivership sale. This is the first of the two: a select service hotel carrying a national flag. The second, a conversion, closed two weeks later.

Buying out of receivership rewards buyers who can move with certainty. The seller is a court-appointed receiver, timelines are set by the process rather than negotiated, and financing contingencies get very little sympathy. Our clients needed a lender who could underwrite two hotel acquisitions in parallel and commit to both.

The purchase also came with a substantial renovation. The property required a $2 million property improvement plan, with the brand standard pre-approved before closing. A hotel under renovation does not produce the cash flow a stabilized one does, so the loan had to carry the property through the work rather than assume it would perform from day one.

The structure did that in three ways. First, a pari passu split: a $5 million SBA 7(a) loan alongside a conventional loan, funding together and sharing collateral, which delivered more proceeds than either program could have on its own. Second, an eighteen month interest-only period ahead of a 300 month amortization, so payments stay light through the renovation. Third, a funded interest reserve, money set aside inside the loan to make the payments during the year the property is being rebuilt.

The total came to just over $6 million, and the deal cleared both the lender’s loan committee and a size-triggered board review to close on its target date.

Krishan Patel, Managing Director of GRP Capital, stated, “Our clients had a clear plan and the experience to execute it, and the job was to build a structure that gave the property room to be renovated before it had to perform. The interest reserve is what makes a deal like this work. Without it you are asking a hotel to service full debt while half of it is out of service. Getting the brand’s approval on the renovation before we closed took the biggest unknown off the table for the lender.”

A hotel purchase that comes with a major renovation is underwritten differently from one that does not. Here is what buyers should understand going in.

Financing a Hotel Purchase With a Major Renovation:

• Expect the lender to underwrite two properties: They are looking at the hotel as it is today and the hotel it will be after the work. Both matter, and the gap between them is where the structure gets built.

• Ask about an interest reserve: If the property will be partly out of service, funded interest inside the loan covers the payments through the disruption. It is the single most useful tool for a purchase-plus-renovation, and it has to be sized at closing, not requested later.

• Understand pari passu: Pairing an SBA loan with a conventional loan that funds alongside it lets a deal reach a size neither program supports by itself. The two loans share collateral and close together. It adds coordination, and it opens up deals that would otherwise not get financed.

• Get the brand’s approval before you close: A renovation scope that the franchisor has already signed off on is a known quantity. One that is still under discussion is a risk the lender has to price, and they will.

• Do not underestimate a receivership timeline: Court-driven sales move on their own calendar. Have your financing genuinely ready rather than merely likely, because there is rarely room to extend.

Why Choose GRP Capital?

Our GRP Capital team specializes in crafting financing solutions tailored to each client’s unique goals. We even have experience with lender dropouts and critically timed funding needs.

Whether you’re purchasing, refinancing, or building from the ground up, our extensive network of lenders ensures you’ll find funding that aligns with your goals and cash flow needs.

Here’s what sets us apart:

  • We save you time by researching and identifying the best funding options for your project.
  • Our expertise spans various loan products—including non-recourse loans, SBA loans, bridge loans, and conventional financing—so you can navigate even the most complex transactions confidently.
  • Beyond lending, we provide strategic guidance on operational decisions that drive long-term business success.
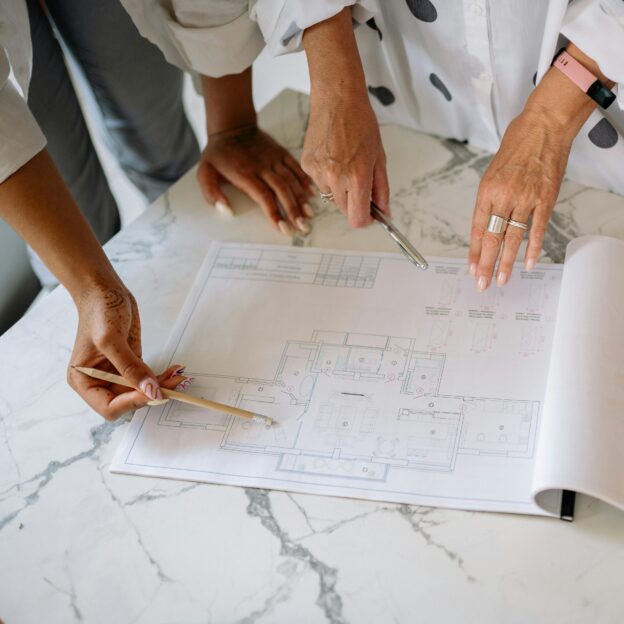
Blueprint for hotel construction loan

Hotel Construction Loan Closes

Hotel construction loans can be complicated. And our Florida clients’ hotel construction loan had hit some roadblocks.

They were busily building a Fairfield Inn, working closely with their general contractor (GC). They had secured an original construction loan to cover the earliest costs of the project. However, their lender ended up not renewing their loan in the midst of the construction process.

Our clients were in a pickle: they were mid-construction but without secure financing. They come to GRP Capital for our advice and for stable lending. We were very pleased to secure permanent funding and they are on target to welcome guests in the very near future.

Rick Patel, GRP Capital President reflected on the loan closing, stating, “We really wanted to help these clients. They know the hospitality market and were well capitalized for this large construction project. They had just experienced a lender drop-off during a critical time. As a result, this could have been an anxious time. Instead, we all worked steadily as a team through a number of issues. We always had faith in our clients and their vision for this Fairfield construction. And we believe we conveyed that story to the lenders, too. Ultimately, I was proud of the client partners and our GRP Capital team.”

Hotel Construction Loans Basics:

• Do your due diligence on a general contractor There is no more important person during the construction process than your GC. Make sure your GC has done a similar project and that they have gone through a lender approval process. Your GC manages every aspect of construction, from hiring subcontractors and staying on top of permitting. Even more importantly, your GC is in charge of producing and maintaining a budget and a an up-to-date log of all costs incurred.

• Engage a knowledgeable attorney: Construction costs can be high. Nevertheless, don’t try to save money by not engaging a knowledgeable attorney early in the process. Expert legal help from the beginning can save you time and money as you get closer to closing. Your lawyer can help guide you through the regulatory maze and also work to mitigate risks in case of disputes and other issues.

• Keep meticulous records on ongoing expenses: Construction loans are a moving target, especially if money is already being spent. Lenders want to reimburse their clients for genuine expenses, but need the expenses organized in specific ways. Your GC and the lender will be collaborating on this. Again, a GC with good interpersonal skills is an asset in this phase, too.

• Don’t start work until you have permits: Clients often get quite excited with a new construction project and want to break ground as soon as the ink is dry on the land purchase. We cannot emphasize enough the important of first obtaining permits. Your attorney and your GC should know the local landscape, in terms of permitting authorities. Take the time now, so everything is above board or you may have early unnecessary costs that you cannot recoup.

Why Choose GRP Capital?

Our GRP Capital team specializes in crafting financing solutions tailored to each client’s unique goals. We even have experience with lender dropouts and critically timed funding needs.

Whether you’re purchasing, refinancing, or building from the ground up, our extensive network of lenders ensures you’ll find funding that aligns with your goals and cash flow needs.

Here’s what sets us apart:

  • We save you time by researching and identifying the best funding options for your project.
  • Our expertise spans various loan products—including non-recourse loans, SBA loans, bridge loans, and conventional financing—so you can navigate even the most complex transactions confidently.
  • Beyond lending, we provide strategic guidance on operational decisions that drive long-term business success.
East texas yellow rose

New Franchise for East Texas Hotel Loan

Our East Texas clients were ready for a new franchise. After operating a Wyndham Baymont property for several years, they were ready to switch to an IHG Garner flagged hotel. The change would bring down their franchise fees. In addition, the new franchise affiliation would also decrease their third party booking fees. Finally, their new loan refinanced previous debt and also covered a lot of the cost of the reflagging.

GRP Capital worked hard to find a lender willing to make a hospitality loan outside of the largest Texas metropolises. Helping the lender understand the benefits of the new franchise was crucial to the underwriting process.

Krishan Patel, Managing Director of GRP Capital stated, “The hotel owners had demonstrated very strong prior management. Their hotel was already healthy and cash flowing. They had done their due diligence and believed that affiliating with a new franchise would have an immediate impact on both their revenues and their expenses. Ultimately, it was our job to tell their story to lenders and find a good match for them. I was very pleased that this loan closed quickly. Hospitality loans outside the major cities often are harder to place and close, but this project was strong from the beginning.”

In the end, having a large lender network allowed GRP Capital to find an appropriate lender and close the loan as quickly as possible.

Are You Considering a New Franchise Affiliation?

• Compare franchise fees: A basic part of a franchise agreement is the percentage of revenues (franchise fee) that come directly to the franchise. So it’s important to compare these numbers. However, be aware that there is variety in the industry. Franchise fees differ not only by flag, but also by type of property (economy, mid-scale, luxury).

• Determine how your franchise affiliation benefits you: Different franchises and different brands within the franchise offer various benefits. Does your franchise have a popular loyalty program? That can really improve your market penetration. Does your brand have general strong marketing and advertising that benefits the franchisees?

• Calculate the costs for reflagging: What will your immediate costs be? You will have to engage in a PIP (Property Improvement Plan). The PIP typically includes refreshing and renovations from the parking lot to the lobby to the guest rooms. And sometimes these are quite extensive. Calculate these costs from furniture to labor, to a big new outdoor sign.

• Consider hiring an attorney to negotiate with the franchise: Your franchise agreement is a long, complex document, that obligates you for many years. An attorney with experience in dealing with franchises can negotiate fees as well as the PIP components to your advantage. This can save time and also position you best in your marketplace.

• Choose the best timing for a transition. A new franchise requires multiple steps. Consider your labor pool and your high season. How can you fit in a transition that is the least disruptive and costly to your business? Do you need to build in some interest only time in your loan if your revenues will be sharply curtailed?

• Learn about all types of loans: There are many types of hospitality loans, including conventional loans, SBA loans, bridge loans and non-recourse loans. Small Business Administration (SBA) loans are often the best matches for hospitality loans. Crucially, the SBA is willing to guarantee a larger variety of hospitality loans, including economy and mid-scale properties.

Why Choose GRP Capital?

Our GRP Capital team specializes in crafting financing solutions tailored to each client’s unique goals.

Whether you’re purchasing, refinancing, or building from the ground up, our extensive network of lenders ensures you’ll find funding that aligns with your goals and cash flow needs.

Here’s what sets us apart:

  • We save you time by researching and identifying the best funding options for your project.
  • Our expertise spans various loan products—including non-recourse loans, SBA loans, bridge loans, and conventional financing—so you can navigate even the most complex transactions confidently.
  • Beyond lending, we provide strategic guidance on operational decisions that drive long-term business success.
Creative Financing for Purchase of Fairfield Inn

Our clients had their eyes on a North Texas Fairfield Inn. The sellers no longer wanted to operate this property as they had moved on to other ventures. They were insistent on a very tight timeline to sell.

The clients came to GRP Capital with good information on the property, very strong prior ownership and management experience, but with this tight timeline. They looked to GRP Capital to match them with a lender and to close before the sellers’ deadline.

Our GRP Capital team worked quickly to find a solution. We investigated all types of loan structures from conventional to SBA. Ultimately, the clients and GRP Capital settled on a two part pari passu loan, consisting of partial SBA financing. This loan met the needs of the clients’ leverage and fit into their business plan. A pari passu loan has components of the debt and each part is on equal footing to the other. That means that no loan is subordinate to one another.

Rick Patel, President of GRP Capital remarked, “I was very happy to see our clients take possession of this Fairfield Inn. It took some extra hard work and creativity to structure this loan. As a result, both the clients and the lender are satisfied with the outcome. The new loan has an SBA guaranteed component. And most importantly, we were able to close the loan pretty fast, keeping both the buyers and the sellers satisfied. We are still very confident in the abilities of our experienced hospitality owners to successfully manage newly acquired properties. That being said, we often have to provide guidance to lenders, helping them to see our client’s vision and to collaborate on a loan structure that will be approved by the leadership of the lender.”

Having a large lender network allowed GRP Capital to find an appropriate lender and close the loan as quickly as possible.

What Do you Need to Close a Loan Quickly?

The right type of project. Refinancing loans can typically close more quickly than construction loans. Purchasing an existing business with a track record makes underwriting easier and hopefully faster. This loan was for the purchase of an existing hotel with clear, reliable statistics about previous performance. Thus, a fast closing was a doable proposition. 

Type of loan matters, too. A fast closing can be possible for a bridge loan. However, SBA loans can sometimes take longer to underwrite. Understand that lenders and agencies’ timelines may lead the process. 

Good Lines of Communication with a Seller, if applicable. When you are purchasing commercial real estate and the business, the lender will need documents and information from the seller. In some cases, the buyers and sellers are a good match and communicate honestly. Sometimes brokers can be the best point of contact. GRP Capital works and communicates with whomever the borrowers determine can get the information, so we can close.

Current guarantor documents. Be prepared to furnish tax returns. If you have other businesses, make sure you have up-to-date financial statements. Gather business debt schedules. Compile two months worth of personal and business bank statements, especially if you will be making an equity injection. Know your personal debt, like car payments and residential mortgages.

Accurate and thoughtful business plans and projections.Spend some time at the beginning of the loan process creating a strong business plan. This should include not only your projections for future income and expenses. It should also include your ideas for operating and managing the business, including marketing, personnel, financial management and maintenance. 

Engage competent professionals right away. Engage an attorney, even before signing a purchase-sale agreement. Tell your accountant of your loan process, and that you may need more recent financials. If you have had a good experience with a title company in the past, make plans to use them again. If you need a survey, get right on that, as these can take some time.

Need more information on creating a strong business plan?

Why Choose GRP Capital?

Our GRP Capital team specializes in crafting financing solutions tailored to each client’s unique goals.

Whether you’re purchasing, refinancing, or building from the ground up, our extensive network of lenders ensures you’ll find funding that aligns with your goals and cash flow needs.

Here’s what sets us apart:

  • We save you time by researching and identifying the best funding options for your project.
  • Our expertise spans various loan products—including non-recourse loans, SBA loans, bridge loans, and conventional financing—so you can navigate even the most complex transactions confidently.
  • Beyond lending, we provide strategic guidance on operational decisions that drive long-term business success.
Texas Independent Hotel Refinance

Ryan Dumas’ client has an independent hotel in central Texas. The owner and her late husband had been operating the hotel for a number of years. They had a private mortgage and wanted to refinance to a more traditional mortgage. Independent hotels often face some barriers in securing financing. But our GRP Capital team was able to find a lender and secure an SBA 7a loan. Ryan was particularly pleased that this SBA loan closed in under 60 days. Truly, this was proof that quick closings can still occur with an SBA product!

Ryan described the closing, saying, “I enjoyed getting to know the owner and her son. They have been working together to maintain and market this independent hotel. I wanted to do everything I could to support these small business owners. They wanted stable, guaranteed funding. The SBA loan was the perfect vehicle for them.”

Special Considerations for an Independent Hotel:

• What are the benefits for keeping this as an independent hotel? Be prepared to show how this hotel operates without the benefit of franchises. Is your location so good, that you do not need the franchise support? How is this property marketed? What are the cost savings of staying independent?

• Hotel statistics: Independent hotels have to work harder to keep track of occupancy, average daily rate and revenue per average room. Be sure that the seller (if you are buying) or you (if you are refinancing) have accurate statistics. Lenders will also often request sales tax payments to verify occupancy statistics.

• To STR or not to STR? Lots of independent properties don’t subscribe to the Smith Travel Report (STR) system. But STR reports can be very helpful as you operate your hotel. You can compare your occupancy and average daily rate to your competitors. Consider if this information would help you in setting rates and making future business plans. It may be worth the money to subscribe, even for a short time.

• Why should I consider an SBA loan?:  Small Business Administration (SBA) loans are often the best matches. For instance, the SBA is willing to guarantee a larger variety of hospitality loans, including economy and mid-scale properties. And many lenders will not consider loans to independent hotels without the SBA guaranty.

• Explore your current lender’s options: If you already have an affordable mortgage, consider why you are interested in refinancing. We can help you determine the costs and the benefits of a new loan.

Why Choose GRP Capital?

Our GRP Capital team specializes in crafting financing solutions tailored to each client’s unique goals.

Whether you’re purchasing, refinancing, or building from the ground up, our extensive network of lenders ensures you’ll find funding that aligns with your goals and cash flow needs.

Here’s what sets us apart:

  • We save you time by researching and identifying the best funding options for your project.
  • Our expertise spans various loan products—including non-recourse loans, SBA loans, bridge loans, and conventional financing—so you can navigate even the most complex transactions confidently.
  • Beyond lending, we provide strategic guidance on operational decisions that drive long-term business success.

Refinance for Carolina Maturing Note

Mortgages are not forever and a maturing note means it is time to take action right away.

Our North Carolina client owned a franchised hotel. His mortgage was maturing and had a balloon payment at the end. Previously, he had renewed his mortgage with his existing lender. However, his lender’s appetite for hospitality lending had changed. The bank leadership had already filled their quota of hospitality loans. They no longer wanted to refinance or renew his maturing note.

We have seen multiple cases of lenders not refinancing or renewing a maturing note. This can be due to the leadership directives of the financial institution, their internal industry quotas or internal risk assessment.

Ultimately, our client turned to GRP Capital to find a suitable lender, one who had room in their portfolio for a hospitality loan.

Krishan Patel, Managing Director of GRP Capital stated, “Our client was hopeful that their current lender would renew their mortgage and was distressed when that was not the case. Throughout the process of finding him a new loan, I personally kept in regular contact with the current lender. We had a good working relationship, even after the date of the note maturation passed. I regularly reassured the lender that we were in the process of securing financing. Fostering a relationship with both his current lender and the new one was critical, as it turned out that our client had a family emergency. This emergency caused a delay in closing, but one which was communicated to all stakeholders.”

Having a large lender network allowed GRP Capital to find an appropriate lender and close the loan as quickly as possible.

Planning for Your Maturing Note:

• Explore your current lender’s options: Well before your note matures, contact your current lender. Inquire if it is possible to renew or refinance and what the details of the new loan would be in terms of monthly costs and ultimate maturity details.

• Determine what is most important to you: Are you concerned about government guarantees? Are you rate-sensitive? Does your loan need to have a certain length? Each borrower has definite priorities. Decide what are your 1-3 most important components of a loan.

• Don’t delay in dealing with a maturing note: Whatever you do, start working on financing at least six months prior to maturation.

• Preserve Your Relationship with Your Current Lender: Pay your mortgage on time. If additional documents are requested like financial statements or an updated appraisal, be compliant and responsive. Ask your lender to prepare a loan history and eventually a payoff statement.

• Get your documents ready. If you are considering a refinance, gather your materials about your business operations (financial statements, business bank statements, budgets and projections). And also assemble the personal documents of any guarantors including three years of tax returns, personal financial statements and information about any other businesses of which you own 20% or more.

• Why should I consider an SBA loan?:  Small Business Administration (SBA) loans are often the best matches. For instance, the SBA is willing to guarantee a larger variety of hospitality loans, including economy and mid-scale properties.

Why Choose GRP Capital?

Our GRP Capital team specializes in crafting financing solutions tailored to each client’s unique goals.

Whether you’re purchasing, refinancing, or building from the ground up, our extensive network of lenders ensures you’ll find funding that aligns with your goals and cash flow needs.

Here’s what sets us apart:

  • We save you time by researching and identifying the best funding options for your project.
  • Our expertise spans various loan products—including non-recourse loans, SBA loans, bridge loans, and conventional financing—so you can navigate even the most complex transactions confidently.
  • Beyond lending, we provide strategic guidance on operational decisions that drive long-term business success.