Category Archives: Teamwork

Bridge Financing Closes for Miami Beach Boutique Hotel

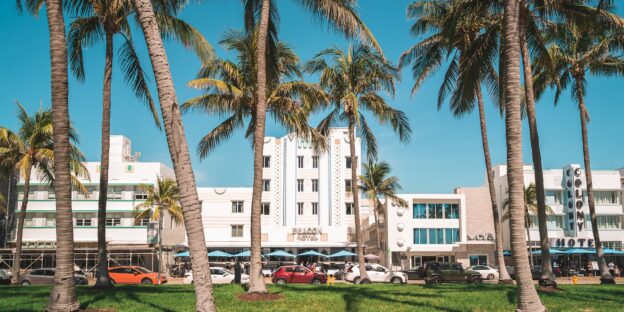
Picture a boutique hotel a block from the ocean on Miami Beach, its Art Deco lines catching the South Beach light. Our clients, an experienced investment group and repeat clients of GRP Capital, were ready to add this property to their portfolio, and they wanted to move quickly.

Boutique hotels in premier markets like Miami Beach are prized assets, but they can be tricky to finance. The purchase price reflects the location and the upside, and the ownership was organized as an investment fund, a structure that not every lender wants to underwrite. Speed mattered too. Our clients needed to close on a tight timeline to secure the property.

A bridge loan was the right tool. Bridge financing gave the borrowers the speed and flexibility to acquire the asset now and execute their business plan, with a clear path to permanent financing once the property stabilizes. GRP Capital placed the sub-$10 million loan with a lender who knew the market and could close fast.

Krishan Patel, Managing Director of GRP Capital, stated, “These are sophisticated, repeat clients who know the Miami Beach market well. The property is a special one, and the ownership structure called for a lender comfortable with an investment fund and a boutique asset. We focused on speed and certainty of close, and we placed the loan with a partner who shared that urgency. It is exactly the kind of premium, complex transaction our team is built to handle.”

Bridge loans are powerful, but they are not the right fit for every borrower or every property. Here is what to understand before you use one.

What to Know About Bridge Financing:

• Bridge loans buy time: A bridge loan is short term, typically twelve to twenty-four months, and lets you acquire or reposition now and refinance once the numbers support it.

• Speed is the advantage: Bridge lenders can often move faster than SBA or conventional lenders. When a purchase depends on a tight closing, that speed can be the difference between getting the property and losing it.

• Price reflects flexibility: Bridge rates run higher than SBA or conventional rates. That premium buys speed, flexibility and a structure that fits complex ownership. Build the cost into your business plan and your exit.

• Have an exit in mind: The strongest bridge borrowers know how they will get out, usually a refinance after stabilization. Plan the exit before you take the loan, not after.

Why Choose GRP Capital?

Our GRP Capital team specializes in crafting financing solutions tailored to each client’s unique goals. We even have experience with lender dropouts and critically timed funding needs.

Whether you’re purchasing, refinancing, or building from the ground up, our extensive network of lenders ensures you’ll find funding that aligns with your goals and cash flow needs.

Here’s what sets us apart:

  • We save you time by researching and identifying the best funding options for your project.
  • Our expertise spans various loan products—including non-recourse loans, SBA loans, bridge loans, and conventional financing—so you can navigate even the most complex transactions confidently.
  • Beyond lending, we provide strategic guidance on operational decisions that drive long-term business success.
Pari Passu Financing Closes for a Central Florida Hotel

Our clients set out to buy two Florida hotels at once, both out of a receivership sale. This is the first of the two: a select service hotel carrying a national flag. The second, a conversion, closed two weeks later.

Buying out of receivership rewards buyers who can move with certainty. The seller is a court-appointed receiver, timelines are set by the process rather than negotiated, and financing contingencies get very little sympathy. Our clients needed a lender who could underwrite two hotel acquisitions in parallel and commit to both.

The purchase also came with a substantial renovation. The property required a $2 million property improvement plan, with the brand standard pre-approved before closing. A hotel under renovation does not produce the cash flow a stabilized one does, so the loan had to carry the property through the work rather than assume it would perform from day one.

The structure did that in three ways. First, a pari passu split: a $5 million SBA 7(a) loan alongside a conventional loan, funding together and sharing collateral, which delivered more proceeds than either program could have on its own. Second, an eighteen month interest-only period ahead of a 300 month amortization, so payments stay light through the renovation. Third, a funded interest reserve, money set aside inside the loan to make the payments during the year the property is being rebuilt.

The total came to just over $6 million, and the deal cleared both the lender’s loan committee and a size-triggered board review to close on its target date.

Krishan Patel, Managing Director of GRP Capital, stated, “Our clients had a clear plan and the experience to execute it, and the job was to build a structure that gave the property room to be renovated before it had to perform. The interest reserve is what makes a deal like this work. Without it you are asking a hotel to service full debt while half of it is out of service. Getting the brand’s approval on the renovation before we closed took the biggest unknown off the table for the lender.”

A hotel purchase that comes with a major renovation is underwritten differently from one that does not. Here is what buyers should understand going in.

Financing a Hotel Purchase With a Major Renovation:

• Expect the lender to underwrite two properties: They are looking at the hotel as it is today and the hotel it will be after the work. Both matter, and the gap between them is where the structure gets built.

• Ask about an interest reserve: If the property will be partly out of service, funded interest inside the loan covers the payments through the disruption. It is the single most useful tool for a purchase-plus-renovation, and it has to be sized at closing, not requested later.

• Understand pari passu: Pairing an SBA loan with a conventional loan that funds alongside it lets a deal reach a size neither program supports by itself. The two loans share collateral and close together. It adds coordination, and it opens up deals that would otherwise not get financed.

• Get the brand’s approval before you close: A renovation scope that the franchisor has already signed off on is a known quantity. One that is still under discussion is a risk the lender has to price, and they will.

• Do not underestimate a receivership timeline: Court-driven sales move on their own calendar. Have your financing genuinely ready rather than merely likely, because there is rarely room to extend.

Why Choose GRP Capital?

Our GRP Capital team specializes in crafting financing solutions tailored to each client’s unique goals. We even have experience with lender dropouts and critically timed funding needs.

Whether you’re purchasing, refinancing, or building from the ground up, our extensive network of lenders ensures you’ll find funding that aligns with your goals and cash flow needs.

Here’s what sets us apart:

  • We save you time by researching and identifying the best funding options for your project.
  • Our expertise spans various loan products—including non-recourse loans, SBA loans, bridge loans, and conventional financing—so you can navigate even the most complex transactions confidently.
  • Beyond lending, we provide strategic guidance on operational decisions that drive long-term business success.
Energy efficient lightbulb

No More Cap on SBA 504 Green Loans

Hot off the presses is this procedural change regarding SBA 504 green loans!

In the past, the SBA 504 green loan program had a $16,500,000 cap. The SBA has announced, that starting in April, they have removed the cap.

Why Is This New Rule Important ?

  • Lifting the cap means that more borrowers can access this funding.
  • No more cap means that Green Loan funding is now available for bigger loans, including construction, acquisition and renovation.
  • The cap removal means that each project has no cap and each borrower has no cap in terms of green loans.

FAQ’s About the SBA 504 Green Loan Program

  • The SBA 504 Green Loan program encourages business owners to be energy efficient and to utilize renewable energy.
  • To be eligible for this funding, you must be creating either more efficiency or transferring your energy consumption to renewable energy in your business.
  • Typically renewable energy must be generating 15% of your energy needs.
  • Energy efficiency must result in utilizing 10% less from non-renewable energy sources.

Matching You with an Appropriate Lender

  • Not every lender has experience with 504 loans including Green loans.
  • Our GRP Capital team already know which lenders are interested in which industries and if they have geographic preferences. We also know which lenders have good reputations and have a high percentage rate of closing loans in a reasonable time frame.
  • Because the 504 program can take a little longer to close, it’s imperative for us to match you with a lender that we both trust.

From Term Sheet to Closing: Understanding the 504 Process

  • Once you have chosen a lender, our team goes into overdrive to get you to closing with a 504 loan.
  • In order to apply for SBA 504 funding, you have to utilize a Community Development Corporation or CDC. The CDC does the initial underwriting and makes sure that the loan will be acceptable to the SBA. We will help you select a CDC.
  • You will also be matched with a senior lender.
  • Our loan processing team, led by Keren Alpert, works directly with the underwriters at the CDC and the lenders as well as other third parties, like appraisers, attorneys, title agents and insurance agents. We know the process all the way until closing.
  • We work directly on your behalf, so you can work on running your business.
Please let us know if you are interested in financing for any of your business projects. Any member of our GRP Capital team would be happy to help you.

Whether you are investing in your first commercial business or expanding your existing portfolio, our in-house experts can help you identify and close on the right loan for your financing needs.
Our primary mission is to provide the most responsive, client-oriented financial services by offering competitive commercial and real estate loan products through a chain of banking and non-banking networks.

From Idea to Closing: The GRP Capital Loan Process

You’ve heard the phrase “the loan process”. What does that even mean to you as a borrower?

We’re glad you asked. Here’s what you need to know!

First Things First: What Is Important to You?

  • Clients come to us by contacting a member of our GRP team, either one of our business associates, our management team or any of our support staff.
  • We consider our first steps like a matchmaking process. First, we need to get to know you. What are the specific goals for your business, what kind of financing are you looking for? How do you envision your business for the short-term and the long-term?

Our Loan Process includes Expert, Personalized Advice

  • Our in-house team will begin to look at your business and your plans. We will ask questions to determine potential roadblocks and evaluate the strength of you and your business as a borrower.
  • Sometimes, we will come back to you with advice to delay seeking financing. We have advised clients to wait for their businesses to show another quarter of profitability. We also have advised clients when we believe that a purchase may be overpriced.
  • If we believe that your business plan looks strong, we will then reach out to our network of lenders to sell your story to them. It’s really important that we advocate for you with the lenders, seeking to find financing that meets your needs.

Matching You with an Appropriate Lender

  • Truly, the GRP Capital “secret sauce” is having relationships with many types of lenders. This is what saves our clients the most time and aggravation.
  • We try to find several lenders so you can choose from among a variety of loans, determining what the most important aspects are (size of loan, type of loan, schedule of repayments, monthly payment, having a relationship with the lender, etc.)
  • We have inside information in many ways, as we already know which lenders are interested in which industries and if they have geographic preferences. We also know which lenders have good reputations and have a high percentage rate of closing loans in a reasonable time frame.
  • Ultimately our lenders know that GRP Capital analyzes all of our potential clients before we begin to search for matching lenders. This analysis saves time for our lenders as they trust our ability to determine the strengths and issues that all of our potential loans have.

From Term Sheet to Closing:

  • Once you have chosen a lender, our team goes into overdrive to get you to closing.
  • Our loan processing team, led by Keren Alpert, works directly with the underwriters as well as other third parties, like appraisers, attorneys, title agents and insurance agents.
  • We work directly on your behalf, so you can work on running your business.
  • Lenders prefer to receive documents that meet their standards, are correct and demonstrate the true nature of the borrowers. Our loan processing team provides that for them.
  • Our clients may take on occasional loans. But our highly experienced loan processing team has seen it all. We can help manage the bumps along the way that can happen and guide you through the steps to take.
  • We know the process all the way until closing. If necessary, we can host closings in our office or support you as you sign documents closer to your home.

What lenders say about us:

“I wish all our clients were GRP Capital clients.”

“You guys rock!”

“They are great to work with and very responsive.”


Please let us know if you are interested in financing for any of your business projects. Any member of our GRP Capital team would be happy to help you.

Whether you are investing in your first commercial business or expanding your existing portfolio, our in-house experts can help you identify and close on the right loan for your financing needs.
Our primary mission is to provide the most responsive, client-oriented financial services by offering competitive commercial and real estate loan products through a chain of banking and non-banking networks.

How and Why we Find Lending Partners

What we do here at GRP Capital is find appropriate lending partners for our clients. But what does that mean? Why does it matter? And why would lending partners even want to work with us?

We’re glad you asked. Here’s what you need to know!

What our Lending Partners Want

  • First, lenders want to make loans in the right “buckets”. Sometimes these are for certain industries, sometimes they are in a certain geographic area. And sometimes, the desirable loans are for a certain size or a specific structure.
  • Lenders prefer to receive documents that meet their standards, are correct and demonstrate the true nature of the borrowers.
  • Lenders want to find qualified borrowers, who can pay back their loans through managing and owning profitable business ventures.

How GRP Capital and Lenders Work Together

  • Probably most importantly, our lenders know that GRP Capital analyzes all of our potential clients before we begin to search for matching lenders. This analysis saves time for our lenders as they trust our ability to determine the strengths and issues that all of our potential loans have.
  • Lenders do not have time to waste. They know that GRP Capital will not bring them loans that are not in their wheelhouse.
  • Finally, lenders are desirous of a smooth path through underwriting and closing. This is where we really do some of our finest work.

How our clients benefit:

  • Because we start off looking for appropriate lenders, we can save our clients time and money as well as finding the loan that is structured for their needs. Each loan is unique. We do not have a cookie cutter approach.
  • Our clients may take on occasional loans. But our highly experienced loan processing team has seen it all. We know exactly the expected quality and content of all of the documents that our lending partners request.
  • Our loan processing team works directly with the bank, the title company, the attorneys, the insurance agents, the accountants. We work hard so our clients can run their businesses. Our clients prefer this setup, and our clients’ comfort is preeminent.

What lenders say about us:

“I wish all our clients were GRP Capital clients.”

“You guys rock!”

“They are great to work with and very responsive.”


Please let us know if you are interested in financing for any of your business projects. Any member of our GRP Capital team would be happy to help you.

Whether you are investing in your first commercial business or expanding your existing portfolio, our in-house experts can help you identify and close on the right loan for your financing needs.
Our primary mission is to provide the most responsive, client-oriented financial services by offering competitive commercial and real estate loan products through a chain of banking and non-banking networks.

Tip for smooth closing: partner with professionals

Everybody wants a smooth closing, including our GRP Capital team! GRP Capital recently closed a loan for a purchase of an 86 unit franchised hotel on the west coast of Florida. GRP Capital Managing Director Krishan Patel as well as GRP Capital President Rick Patel worked closely with our client. They also worked with his team of highly competent and trusted professionals. As a result, we closed quickly and without too many hiccups.  

Smooth Closing: How we can partner with your professionals: 

• Accurate and Appropriate Financials : While many small business owners prepare their own financials, lenders prefer professionally prepared financials. For this loan, we worked carefully with our client’s CPA. Together we analyzed the financials of the hotel being purchased. We also pre-underwrote the financials of various businesses owned by our client. We wanted to show the lender the true potential revenue value of the hotel. In addition, we demonstrated the ability of our borrower to make payments on a new loan.

•  Saving Our Clients Time: The lender requested many documents. Being able to work directly with the CPA allowed our client to run his businesses. Furthermore, he trusted us and his CPA to work on his behalf. As a result, he didn’t have to be involved in every email or conversation.

•  Excellent Attorneys Make for Excellent Closings:  We notice that having a trusted attorney at closing makes a difference. They look out for our clients’ interest and are able to amend documents quickly. If necessary, they can run title and even escrow funds. We recommend that all of our clients engage an attorney. Clients are often spending a lot of money when seeking financing. Paying for an attorney is an investment towards a smooth closing and protects client’s interests.

Rick Patel upon closing this loan stated, “We know this client well and have worked with his professional team, too. They are very responsive to our phone calls and e-mails not just from me, but from Keren Alpert, our loan processor, too. As a result, our client trusts that we are doing the work in the background, so he can run his business.“

Our GRP Capital team specializes in finding the right lender for each project. We save our clients time and money, as we research  the best choices for their funding sources. Our experience allows our clients to find funding that is project-appropriate and will allow for sufficient cash flow. If you are considering becoming a first-time (or second or third time!) buyer or refinancing a current loan, we can assist you.

GRP Capital Team coming to AAHOAcon25

Our team is excited to attend the AAHOAcon25, to be held in New Orleans from April 15th through April 17th. We can’t wait to be in NoLa to network and celebrate with all of you.

What makes the AAHOA conference so important to us?

Making Connections with Clients

We love talking on the phone and emailing our clients and lending partners. We even learn from each other on Zoom and conference calls. But AAHOACon25 lets us see each other face to face. We have the opportunity to hang out with our clients, to hear about their successes and challenges and their dreams. We find the time to get to know our clients better and figure out how we can help these entrepreneurs realize their aspirations.

Building our Lender Network 

We also strengthen our connections with lenders. Lenders typically love our business model. What’s not to love? We partner with fabulous clients, pre-package their loans and do the bulk of the document collection during underwriting. Because we know the lenders’ wishlist for loans (size, geographic area, debt coverage, what types of hospitality properties, other industry loans), we only bring them what they are looking for. Adding to our lender network benefits everyone, providing more options for a variety of financing.

Learning Together

There is much to learn from many experts. We can take away a ton of knowledge from attending the huge variety of educational opportunities at the AAHOA conference. Even more important, our learning is enhanced by being surrounded by our peers and mentors, clients and lending partners, old friends and new acquaintances.

GRP Capital President Rick Patel notes, “Our team will again be at AAHOA Convention; it’s an important time in the hospitality industry and we want to make sure that we all meet and get to know the people who can use our assistance. It’s the highlight of our year in many ways.”

Are you wanting some one-on-one time or free business consulting during the conference? Make connections with our GRP Capital team members now and we can reserve time to explore your business concerns and future solutions.

Downtown Orlando AAHOAcon24

Entire GRP Capital Team coming to AAHOAcon24

Our entire team is excited to attend the AAHOAcon24, to be held in Orlando, Florida from April 2nd through April 5th. We are thrilled to be in our own Sunshine State to network and celebrate with all of you.

What makes the AAHOA conference so important to us?

Making Connections with Clients

We love talking on the phone and emailing our clients and lending partners. We even learn from each other on Zoom and conference calls. But AAHOACon24 lets us see each other face to face. We have the opportunity to hang out with our clients, to hear about their successes and challenges and their dreams. We find the time to get to know our clients better and figure out how we can help these entrepreneurs realize their aspirations.

Building our Lender Network 

We also strengthen our connections with lenders. Lenders typically love our business model. What’s not to love? We partner with fabulous clients, pre-package their loans and do the bulk of the document collection during underwriting. Because we know the lenders’ wishlist for loans (size, geographic area, debt coverage, what types of hospitality properties, other industry loans), we only bring them what they are looking for. Adding to our lender network benefits everyone, providing more options for a variety of financing.

Learning Together

There is much to learn from many experts. We can take away a ton of knowledge from attending the huge variety of educational opportunities at the AAHOA conference. Even more important, our learning is enhanced by being surrounded by our peers and mentors, clients and lending partners, old friends and new acquaintances.

GRP Capital President Rick Patel notes, “Our entire team will again be at AAHOA Convention; it’s an important time in the hospitality industry and we want to make sure that we all meet and get to know the people who can use our assistance. It’s the highlight of our year in many ways.”

Are you wanting some one-on-one time or free business consulting during the conference? Make connections with our GRP Capital team members now and we can reserve time to explore your business concerns and future solutions.

Entire GRP Capital Team coming to AAHOAcon23

Our entire team is excited to attend the AAHOAcon23, to be held in Los Angeles April 11-14th. California, here we come!

What makes the AAHOA conference so important to us?

Making Connections with Clients

We love talking on the phone and emailing our clients and lending partners. We even learn from each other on Zoom and conference calls. But AAHOACon23 lets us see each other face to face. We have the opportunity to hang out with our clients, to hear about their successes and challenges and their dreams. We find the time to get to know our clients better and figure out how we can help these entrepreneurs realize their aspirations.

Building our Lender Network 

We also strengthen our connections with lenders. Lenders typically love our business model. What’s not to love? We partner with fabulous clients, pre-package their loans and do the bulk of the document collection during underwriting. Because we know the lenders’ wishlist for loans (size, geographic area, debt coverage, what types of hospitality properties, other industry loans), we only bring them what they are looking for. Adding to our lender network benefits everyone, providing more options for a variety of financing.

Learning Together

There is much to learn from many experts. We can take away a ton of knowledge from attending the huge variety of educational opportunities at the AAHOA conference. Even more important, our learning is enhanced by being surrounded by our peers and mentors, clients and lending partners, old friends and new acquaintances.

GRP Capital President Rick Patel notes, “Our entire team will be at AAHOA Convention; it’s an important time in the hospitality industry and we want to make sure that we all meet and get to know the people who can use our assistance. It’s the highlight of our year in many ways.”

Are you wanting some one-on-one time or free business consulting during the conference? Make connections with our GRP Capital team members now and we can reserve time to explore your business concerns and future solutions.

Wallet for personal financial statement blog

How to Fill out a Personal Financial Statement (PFS)

Lenders typically request that borrowers fill out a personal financial statement (PFS) when applying for a loan. This personal financial statement can vary somewhat, although the SBA uses Form 413. A PFS shows the bank a borrower’s cash position, how much liquidity they have to take on a new loan and their ability to pay back future loans. It’s important to understand the typical questions on a PFS, so you can fill them out accurately. Below are components of a PFS that are most confusing to our clients.

The Asset Portion of the PFS:

• What is Cash on Hand? Cash on hand is money that you have in checking and savings accounts and in cash on your person that is immediately available to you (liquid). Be prepared to furnish bank statements to support your cash availability. This is different from stocks and bonds, IRA’s or even Bitcoin.

• What do I need to know about my life insurance policies? You only need to declare life insurance policies if you have a whole life policy with a cash surrender value. So if you have a term life policy, you cannot consider it as a current asset, as it has no cash value.

• Real Estate and Automobiles as Assets:  Estimate the value of the automobiles you have and any real estate you own. This real estate includes your residences (primary and vacation homes). In addition, you will need to calculate the value of any commercial real estate you own. If you are a partner in a business that owns real estate, you can only claim the value of the real estate equal to the percentage of the business you own.

Declaring Liabilities on a PFS:

• Notes Payable and Installment Accounts:  Gather all of your personal loan and credit card statements to fill out the liabilities section of the PFS. You’ll need to know what your payments and balances are.

• Car Loans and Mortgage Loans: Your automobiles and real estate are assets, but if you owe money on them, they are also liabilities. Complete your PFS by stating what the payments and balances are, the interest rate, and in the case of mortgages, who the lender is and when the mortgage will be paid off. If your commercial real estate is for a business in which you are a partner, you only need to declare the percentage of the mortgage equal to your ownership percentage.

• Loans Against Life Insurance: Again, this is only applicable if you have a whole life policy (not a term policy) and you have taken out a loan against the cash value of the policy. Otherwise, this should be left blank.

• Unpaid Taxes: Most lenders would prefer that you pay off overdue taxes. But you can show a small amount on your PFS and work through that process prior to closing.

Net Worth:

Net worth is an equation. If you add up all your assets, and subtract all your liabilities, that is your net worth. It does not include your salary or your earning potential, just your declarable assets and liabilities.

We work closely with our clients to make sure the PFS is accurate. If you are considering a loan for purchase or refinance and would like to discuss your plans, feel free to contact our team. We will get to know you and your business objectives. Then we will recommend the best loans for you to consider. Initial consultations are free.