Tag Archives: sba loan

Pari Passu Financing Closes for a Central Florida Hotel

Our clients set out to buy two Florida hotels at once, both out of a receivership sale. This is the first of the two: a select service hotel carrying a national flag. The second, a conversion, closed two weeks later.

Buying out of receivership rewards buyers who can move with certainty. The seller is a court-appointed receiver, timelines are set by the process rather than negotiated, and financing contingencies get very little sympathy. Our clients needed a lender who could underwrite two hotel acquisitions in parallel and commit to both.

The purchase also came with a substantial renovation. The property required a $2 million property improvement plan, with the brand standard pre-approved before closing. A hotel under renovation does not produce the cash flow a stabilized one does, so the loan had to carry the property through the work rather than assume it would perform from day one.

The structure did that in three ways. First, a pari passu split: a $5 million SBA 7(a) loan alongside a conventional loan, funding together and sharing collateral, which delivered more proceeds than either program could have on its own. Second, an eighteen month interest-only period ahead of a 300 month amortization, so payments stay light through the renovation. Third, a funded interest reserve, money set aside inside the loan to make the payments during the year the property is being rebuilt.

The total came to just over $6 million, and the deal cleared both the lender’s loan committee and a size-triggered board review to close on its target date.

Krishan Patel, Managing Director of GRP Capital, stated, “Our clients had a clear plan and the experience to execute it, and the job was to build a structure that gave the property room to be renovated before it had to perform. The interest reserve is what makes a deal like this work. Without it you are asking a hotel to service full debt while half of it is out of service. Getting the brand’s approval on the renovation before we closed took the biggest unknown off the table for the lender.”

A hotel purchase that comes with a major renovation is underwritten differently from one that does not. Here is what buyers should understand going in.

Financing a Hotel Purchase With a Major Renovation:

• Expect the lender to underwrite two properties: They are looking at the hotel as it is today and the hotel it will be after the work. Both matter, and the gap between them is where the structure gets built.

• Ask about an interest reserve: If the property will be partly out of service, funded interest inside the loan covers the payments through the disruption. It is the single most useful tool for a purchase-plus-renovation, and it has to be sized at closing, not requested later.

• Understand pari passu: Pairing an SBA loan with a conventional loan that funds alongside it lets a deal reach a size neither program supports by itself. The two loans share collateral and close together. It adds coordination, and it opens up deals that would otherwise not get financed.

• Get the brand’s approval before you close: A renovation scope that the franchisor has already signed off on is a known quantity. One that is still under discussion is a risk the lender has to price, and they will.

• Do not underestimate a receivership timeline: Court-driven sales move on their own calendar. Have your financing genuinely ready rather than merely likely, because there is rarely room to extend.

Why Choose GRP Capital?

Our GRP Capital team specializes in crafting financing solutions tailored to each client’s unique goals. We even have experience with lender dropouts and critically timed funding needs.

Whether you’re purchasing, refinancing, or building from the ground up, our extensive network of lenders ensures you’ll find funding that aligns with your goals and cash flow needs.

Here’s what sets us apart:

  • We save you time by researching and identifying the best funding options for your project.
  • Our expertise spans various loan products—including non-recourse loans, SBA loans, bridge loans, and conventional financing—so you can navigate even the most complex transactions confidently.
  • Beyond lending, we provide strategic guidance on operational decisions that drive long-term business success.
Repeat Client Purchases Maine Hotel

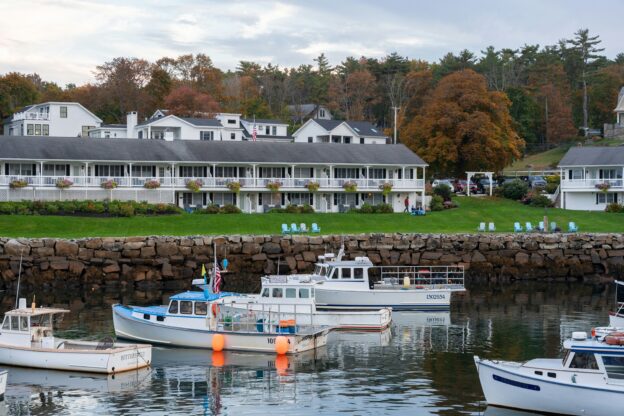
Our client partners had their eyes on a Maine hotel. One of the partners is already experienced in the New England hospitality business. He even recently closed another hotel purchase with GRP Capital. He and his partner thought that this Maine hotel was just what they were after: a stable hotel that could quickly become more profitable.

The new hotel is located in a charming New England town with a nearby college.

Ryan Dumas, Senior Associate was very pleased to close this loan “I know one of the partners really well. He’s honest and a good business person. He has a vision to purchase New England properties, particularly those that can easily become more profitable. His business plan was strong and the lenders believed in the project. The partners have a clear and doable set of steps to increase the revenue of this hotel right away.”

Business Plan Basics and this Maine Hotel:

• Understand your hotel’s seasons as you take action: Many hotels are in locations that have seasonality. High season for a Maine hotel is different than the South Florida hospitality landscape. A strong business plan recognizes any seasonality and has a strategy for both high season and low season. This plan incorporates staffing, marketing and setting rates.

• Really understand the STR report of the property you are buying or refinancing. Smith Travel Reports or STR reporting gives you information not just about the property you are investigating. STR reports also show you that property’s position in the marketplace. You can compare this hotel to others nearby in terms of occupancy and daily rates. This is incredibly useful information for a potential buyer. You can use the STR numbers to set realistic goals and create a business plan that works towards those targets. If the hotel is not a STR subscriber, make sure that hotel statistics are accurate and complete.

• Highlight your previous positive experiences. This hotel owner had experience with underperforming properties. Therefore, the partners could quickly delineate the needed changes which would have an immediate impact on both revenues and expenses. If you have successfully operated this type of business or another business but in this marketplace, indicate that in your business plan. Explain how you have enhanced revenue or minimized surprise expenses in your previous business endeavors.

Why Choose GRP Capital?

Our GRP Capital team specializes in crafting financing solutions tailored to each client’s unique goals.

Whether you’re purchasing, refinancing, or building from the ground up, our extensive network of lenders ensures you’ll find funding that aligns with your goals and cash flow needs.

Here’s what sets us apart:

  • We save you time by researching and identifying the best funding options for your project.
  • Our expertise spans various loan products—including SBA loans, bridge loans, and conventional financing—so you can navigate even the most complex transactions confidently.
  • Beyond lending, we provide strategic guidance on operational decisions that drive long-term business success.
New Mexico Native American art

New Mexico Hotel Refi Offers Low Rates

GRP Capital New Mexico hotel owners secured financing that offered market-best low rates.

Ryan Dumas and the GRP Capital team worked very diligently with this client group. The partners really had one overarching goal: securing lower rates. Their current note had a high interest rate. Therefore, their new loan needed to show significant savings. An SBA 504 loan was the best choice for them. It offered stable, low rates. More importantly, the SBA guarantee made the loan more attractive to lenders.

Senior Associate Ryan Dumas reflected on the path to get the loan closed. “Our clients are experienced in this marketplace. However, New Mexico is a smaller market. We needed the SBA to help support this loan in order to entice a lender. I was thrilled that this new loan is a full 3 points lower than the clients’ previous mortgage. They will be saving serious money, which they can use personally or professionally. They will continue to be a significant employer and business in their small town.”

Using an SBA 504 to Access Low Rates

  • GRP Capital has connections with multiple CDC’s across the nation and the lenders who are interested in 504 loans.
  • The 504 program requires utilizing a Certified Development Company (CDC). The CDC is SBA’s community-based nonprofit partners who promote economic development within their communities. CDCs are certified and regulated by SBA.
  • The SBA 504 structure guarantees loans, so that lenders face lower risks.
  • We are very careful to ensure sufficient SBA eligibility prior to choosing a loan vehicle. If you have any questions about what this means, please contact us.
  • In many marketplaces, the SBA guaranteed loans are competitive with conventional loans.
  • SBA loans may often be the best bet for achieving lower interest rates.

Contact Ryan if you are considering SBA funding, 504 Loans, Green Loans or any other loan products.

Our GRP Capital team specializes in finding the right lender for each project. We save our clients time and money, as we research the best choices for their funding sources. Our experience allows our clients to find funding that is project-appropriate and will allow for sufficient cash flow. Whether you are looking to refinance, purchase or engage in construction, we would love to discuss your business plans with you. If you are considering becoming a first-time (or second or third time!) buyer, we can assist you.

Third Beach Hotel Buy

Ryan Dumas and the GRP Capital team are very happy to have closed another Carolina beach hotel loan. Our clients decided to embark on an SBA 504 loan, utilizing the Green program. They will be adding solar panels to their hotel, reducing electric consumption and bills.

Senior Associate Ryan Dumas and our entire team collaborated with our very motivated clients to get this somewhat complex loan closed.

Ryan, who has now closed three loans with this client, stated:

I really value this client group and was so happy that they came to me for a third time to find financing. The lead borrower has a lot of knowledge about this resort community. Of course, he is an excellent hotelier. It was critical to place this loan with the SBA 504 Green Program. When you use the Green program, it preserves eligibility. Since the partners have other SBA loans, they didn’t max out with this loan. And now they are installing solar panels, which are ideal for sunny climates. Even more importantly, this kept the loan affordable, as the partners have other future business deals in mind.

Advantages of the Green Program for a Beach Hotel

  • There are certain limits to an SBA 504 loan. However, utilizing a Green Loan does not “count against” your eligibility.
  • Green Loans can be used to reduce energy costs and to utilize renewable energy. A sunny and/or windy location near a beach is perfectly situated.
  • We are very careful to ensure sufficient SBA eligibility prior to choosing a loan vehicle. If you have any questions about what this means, please contact us.
  • The 504 program requires utilizing a Certified Development Company (CDC). The CDC is SBA’s community-based nonprofit partners who promote economic development within their communities. CDCs are certified and regulated by SBA.
  • GRP Capital has connections with multiple CDC’s across the nation and the lenders who are interested in 504 loans.

Contact our team if you are considering SBA funding, 504 Loans, Green Loans or any other loan products. We can help you determine the right mix of loan types for all of your business financing needs.

Our GRP Capital team specializes in finding the right lender for each project. We save our clients time and money, as we research the best choices for their funding sources. Our experience allows our clients to find funding that is project-appropriate and will allow for sufficient cash flow. Whether you are looking to refinance, purchase or engage in construction, we would love to discuss your business plans with you. If you are considering becoming a first-time (or second or third time!) buyer, we can assist you.

Partner Group Buys New York Hotel

The New York hotel marketplace can be complex. Real estate taxes and procedures can be complicated with commercial real estate deals. But our clients were ready to purchase a New York hotel. They perceived that the state has largely bounced back from COVID, especially upstate.

Working closely with our entire team, they purchased the hotel and are ready to take advantage of summer high season. Our clients selected SBA financing for their loan. As a result, our team needed to be nimble, especially with changes in the SBA administration. Everybody was particularly mindful of the rules for SBA eligibility.

Senior Associate Ryan Dumas was excited to close this loan. He remarked:

My clients were ready to purchase this upstate New York hotel and have a good handle on this specific market. An SBA loan was the best loan vehicle for them. However, we were all aware of changes in the SBA. We had to make changes to the loan details a couple of times, but I was thrilled to get this across the finish line. I know my clients will own and manage this property in ways that maximize revenue, while keeping an eye on expenses.

Is an SBA Loan in Your Future?

  • The Small Business Association (SBA) has multiple loan programs and guarantees. They each have their own eligibility standards.
  • SBA loans may be the best choice for certain markets and for certain types of hospitality properties, especially hotels with external corridors.
  • Because of changes to SBA staffing and increased scrutiny of non citizen partners, borrowers should be aware that the SBA approval can take three to four weeks, in addition to lender underwriting and approval. (These can happen simultaneously.)
  • SBA also limits the amount of SBA debt each guarantor can have. This debt load does not include prior EIDL’s (Economic Injury Disaster Loans).

Contact our team if you are considering SBA funding or any other loan products. We can help you determine the right mix of loan types for all of your business financing needs.

Our GRP Capital team specializes in finding the right lender for each project. We save our clients time and money, as we research the best choices for their funding sources. Our experience allows our clients to find funding that is project-appropriate and will allow for sufficient cash flow. Whether you are looking to refinance, purchase or engage in construction, we would love to discuss your business plans with you. If you are considering becoming a first-time (or second or third time!) buyer, we can assist you.