Tag Archives: Commercial

Bridge Financing Closes for Miami Beach Boutique Hotel

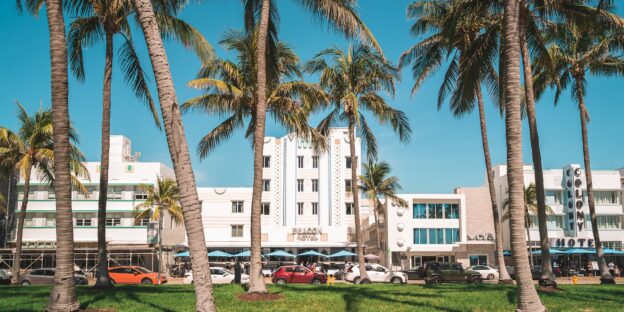
Picture a boutique hotel a block from the ocean on Miami Beach, its Art Deco lines catching the South Beach light. Our clients, an experienced investment group and repeat clients of GRP Capital, were ready to add this property to their portfolio, and they wanted to move quickly.

Boutique hotels in premier markets like Miami Beach are prized assets, but they can be tricky to finance. The purchase price reflects the location and the upside, and the ownership was organized as an investment fund, a structure that not every lender wants to underwrite. Speed mattered too. Our clients needed to close on a tight timeline to secure the property.

A bridge loan was the right tool. Bridge financing gave the borrowers the speed and flexibility to acquire the asset now and execute their business plan, with a clear path to permanent financing once the property stabilizes. GRP Capital placed the sub-$10 million loan with a lender who knew the market and could close fast.

Krishan Patel, Managing Director of GRP Capital, stated, “These are sophisticated, repeat clients who know the Miami Beach market well. The property is a special one, and the ownership structure called for a lender comfortable with an investment fund and a boutique asset. We focused on speed and certainty of close, and we placed the loan with a partner who shared that urgency. It is exactly the kind of premium, complex transaction our team is built to handle.”

Bridge loans are powerful, but they are not the right fit for every borrower or every property. Here is what to understand before you use one.

What to Know About Bridge Financing:

• Bridge loans buy time: A bridge loan is short term, typically twelve to twenty-four months, and lets you acquire or reposition now and refinance once the numbers support it.

• Speed is the advantage: Bridge lenders can often move faster than SBA or conventional lenders. When a purchase depends on a tight closing, that speed can be the difference between getting the property and losing it.

• Price reflects flexibility: Bridge rates run higher than SBA or conventional rates. That premium buys speed, flexibility and a structure that fits complex ownership. Build the cost into your business plan and your exit.

• Have an exit in mind: The strongest bridge borrowers know how they will get out, usually a refinance after stabilization. Plan the exit before you take the loan, not after.

Why Choose GRP Capital?

Our GRP Capital team specializes in crafting financing solutions tailored to each client’s unique goals. We even have experience with lender dropouts and critically timed funding needs.

Whether you’re purchasing, refinancing, or building from the ground up, our extensive network of lenders ensures you’ll find funding that aligns with your goals and cash flow needs.

Here’s what sets us apart:

  • We save you time by researching and identifying the best funding options for your project.
  • Our expertise spans various loan products—including non-recourse loans, SBA loans, bridge loans, and conventional financing—so you can navigate even the most complex transactions confidently.
  • Beyond lending, we provide strategic guidance on operational decisions that drive long-term business success.
Pari Passu Financing Closes for a Central Florida Hotel

Our clients set out to buy two Florida hotels at once, both out of a receivership sale. This is the first of the two: a select service hotel carrying a national flag. The second, a conversion, closed two weeks later.

Buying out of receivership rewards buyers who can move with certainty. The seller is a court-appointed receiver, timelines are set by the process rather than negotiated, and financing contingencies get very little sympathy. Our clients needed a lender who could underwrite two hotel acquisitions in parallel and commit to both.

The purchase also came with a substantial renovation. The property required a $2 million property improvement plan, with the brand standard pre-approved before closing. A hotel under renovation does not produce the cash flow a stabilized one does, so the loan had to carry the property through the work rather than assume it would perform from day one.

The structure did that in three ways. First, a pari passu split: a $5 million SBA 7(a) loan alongside a conventional loan, funding together and sharing collateral, which delivered more proceeds than either program could have on its own. Second, an eighteen month interest-only period ahead of a 300 month amortization, so payments stay light through the renovation. Third, a funded interest reserve, money set aside inside the loan to make the payments during the year the property is being rebuilt.

The total came to just over $6 million, and the deal cleared both the lender’s loan committee and a size-triggered board review to close on its target date.

Krishan Patel, Managing Director of GRP Capital, stated, “Our clients had a clear plan and the experience to execute it, and the job was to build a structure that gave the property room to be renovated before it had to perform. The interest reserve is what makes a deal like this work. Without it you are asking a hotel to service full debt while half of it is out of service. Getting the brand’s approval on the renovation before we closed took the biggest unknown off the table for the lender.”

A hotel purchase that comes with a major renovation is underwritten differently from one that does not. Here is what buyers should understand going in.

Financing a Hotel Purchase With a Major Renovation:

• Expect the lender to underwrite two properties: They are looking at the hotel as it is today and the hotel it will be after the work. Both matter, and the gap between them is where the structure gets built.

• Ask about an interest reserve: If the property will be partly out of service, funded interest inside the loan covers the payments through the disruption. It is the single most useful tool for a purchase-plus-renovation, and it has to be sized at closing, not requested later.

• Understand pari passu: Pairing an SBA loan with a conventional loan that funds alongside it lets a deal reach a size neither program supports by itself. The two loans share collateral and close together. It adds coordination, and it opens up deals that would otherwise not get financed.

• Get the brand’s approval before you close: A renovation scope that the franchisor has already signed off on is a known quantity. One that is still under discussion is a risk the lender has to price, and they will.

• Do not underestimate a receivership timeline: Court-driven sales move on their own calendar. Have your financing genuinely ready rather than merely likely, because there is rarely room to extend.

Why Choose GRP Capital?

Our GRP Capital team specializes in crafting financing solutions tailored to each client’s unique goals. We even have experience with lender dropouts and critically timed funding needs.

Whether you’re purchasing, refinancing, or building from the ground up, our extensive network of lenders ensures you’ll find funding that aligns with your goals and cash flow needs.

Here’s what sets us apart:

  • We save you time by researching and identifying the best funding options for your project.
  • Our expertise spans various loan products—including non-recourse loans, SBA loans, bridge loans, and conventional financing—so you can navigate even the most complex transactions confidently.
  • Beyond lending, we provide strategic guidance on operational decisions that drive long-term business success.
Large Balance Sheet Refinance Closes for Coral Springs Multifamily

Our clients, a seasoned ownership group, needed to refinance a 400 unit multifamily community in Coral Springs, Florida. The property was performing, the business plan was working, and the existing debt was coming due. What they needed was a lender who could underwrite a transaction of real size in one of the most competitive rental markets in the country.

Large multifamily refinances live in a different part of the lending market than the deals that fill much of the industry. As the loan amount climbs, the pool of willing lenders narrows, the underwriting grows more demanding, and the diligence calendar runs longer. Our clients depended on GRP Capital to find the right lending partner and to tell the story of a well run property with a proven ownership group behind it.

The property made the case. At roughly 94 percent occupancy across a mix of one, two and three bedroom units, the community had steady in place cash flow. Ownership had also been working through a unit renovation program, upgrading interiors in phases and moving those units to a higher rent tier as they turned. That is the kind of disciplined value add story lenders want to see, because it shows an operator who can execute without stretching the balance sheet.

Rather than an agency execution, this refinance was best served by a balance sheet loan. Balance sheet financing delivered the proceeds, the structure and the certainty of close the borrowers needed, without the constraints that come with other programs. The result was a $52.0 million loan that closed in August 2026, the largest single closing in GRP Capital’s history.

Rick Patel, GRP Capital President, commented, “This $52.0 million refinance is the largest loan our team has closed, and it showcased our GRP Capital team’s ability to handle and close a transaction of institutional size. Large loans require a different level of underwriting, coordination and patience. Our team worked closely with the borrowers, the lender and the third party professionals to bring every piece together and close on schedule.”

Veeraj Patel, Vice President of Commercial Loans, who led the placement, added, “Our clients run this property extremely well, and my job was to make sure the lender saw that clearly. We built a package around the occupancy, the rent roll and the renovation program so there were no surprises once the file reached underwriting. A balance sheet execution gave the borrowers the proceeds and the certainty of close they were after. This is exactly the kind of multifamily transaction our team is built to underwrite.”

Refinancing a large multifamily property is not simply a bigger version of refinancing a small one. The lender pool is different, the diligence runs deeper, and the coordination among borrower, lender and professionals has to be tight. Here is what seasoned operators keep in mind when they step up in size.

Refinancing a Large Multifamily Property:

• Start the conversation early: Large refinances take longer than small ones. Appraisals, environmental reports, property condition assessments and title work all take time, and credit committees move on their own calendar. Give yourself six months ahead of a maturity, not six weeks.

• Keep your rent roll and your financials clean: Lenders will pull your rent roll, your trailing twelve month statements and your unit statistics, and they will expect those numbers to agree with one another. Reconciled records shorten underwriting more than almost anything else you control.

• Document your renovation program: If you are upgrading units and pushing rents, show the work: the scope, the cost per unit, the premium achieved and how many units are complete. A documented value add story is an asset in underwriting. An undocumented one is a question mark.

• Protect your occupancy through the process: Lenders want to see a healthy, stable occupancy rate at closing, not only at application. A dip during diligence invites a second look at your proceeds.

• Know which lenders are actually in the market: Not every bank has appetite for large multifamily exposure, and appetite shifts quarter to quarter. Knowing who is lending at your size, in your market, right now is what protects your closing timeline.

Why Choose GRP Capital?

Our GRP Capital team specializes in crafting financing solutions tailored to each client’s unique goals. We even have experience with lender dropouts and critically timed funding needs.

Whether you’re purchasing, refinancing, or building from the ground up, our extensive network of lenders ensures you’ll find funding that aligns with your goals and cash flow needs.

Here’s what sets us apart:

  • We save you time by researching and identifying the best funding options for your project.
  • Our expertise spans various loan products—including non-recourse loans, SBA loans, bridge loans, and conventional financing—so you can navigate even the most complex transactions confidently.
  • Beyond lending, we provide strategic guidance on operational decisions that drive long-term business success.

Repeat Client Purchases Maine Hotel

Our client partners had their eyes on a Maine hotel. One of the partners is already experienced in the New England hospitality business. He even recently closed another hotel purchase with GRP Capital. He and his partner thought that this Maine hotel was just what they were after: a stable hotel that could quickly become more profitable.

The new hotel is located in a charming New England town with a nearby college.

Ryan Dumas, Senior Associate was very pleased to close this loan “I know one of the partners really well. He’s honest and a good business person. He has a vision to purchase New England properties, particularly those that can easily become more profitable. His business plan was strong and the lenders believed in the project. The partners have a clear and doable set of steps to increase the revenue of this hotel right away.”

Business Plan Basics and this Maine Hotel:

• Understand your hotel’s seasons as you take action: Many hotels are in locations that have seasonality. High season for a Maine hotel is different than the South Florida hospitality landscape. A strong business plan recognizes any seasonality and has a strategy for both high season and low season. This plan incorporates staffing, marketing and setting rates.

• Really understand the STR report of the property you are buying or refinancing. Smith Travel Reports or STR reporting gives you information not just about the property you are investigating. STR reports also show you that property’s position in the marketplace. You can compare this hotel to others nearby in terms of occupancy and daily rates. This is incredibly useful information for a potential buyer. You can use the STR numbers to set realistic goals and create a business plan that works towards those targets. If the hotel is not a STR subscriber, make sure that hotel statistics are accurate and complete.

• Highlight your previous positive experiences. This hotel owner had experience with underperforming properties. Therefore, the partners could quickly delineate the needed changes which would have an immediate impact on both revenues and expenses. If you have successfully operated this type of business or another business but in this marketplace, indicate that in your business plan. Explain how you have enhanced revenue or minimized surprise expenses in your previous business endeavors.

Why Choose GRP Capital?

Our GRP Capital team specializes in crafting financing solutions tailored to each client’s unique goals.

Whether you’re purchasing, refinancing, or building from the ground up, our extensive network of lenders ensures you’ll find funding that aligns with your goals and cash flow needs.

Here’s what sets us apart:

  • We save you time by researching and identifying the best funding options for your project.
  • Our expertise spans various loan products—including SBA loans, bridge loans, and conventional financing—so you can navigate even the most complex transactions confidently.
  • Beyond lending, we provide strategic guidance on operational decisions that drive long-term business success.