Category Archives: Hospitality

Checklist with hand

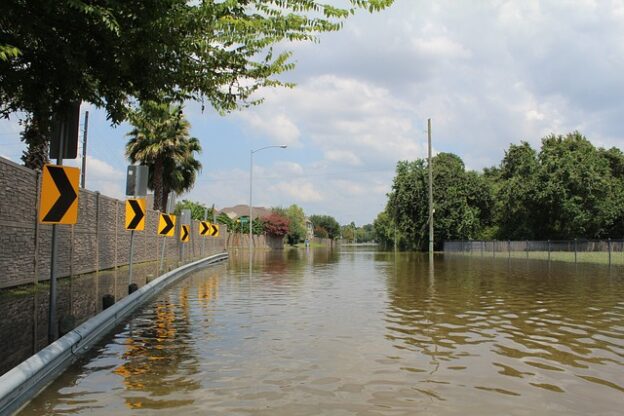
Business Recovery After the Hurricane: A Checklist

Let’s talk about business recovery after a major weather even.

We still have six weeks to go in the hurricane season! But many of our clients have already experienced physical damage as well as interruption to their businesses including loss of revenue.

What are the Most Important Tasks for Business Recovery?

Communicate with Your Lender!

  • Believe it or not, if you have commercial real estate, contact your lender right away.
  • Let the lender know about any damages and how you think this might affect your business. Be honest about what the challenges could be in terms of both revenue and expenses.
  • Your lender may reduce or delay your regular mortgage payments for a short time.
  • If GRP Capital helped you find a loan, we are happy to work directly with the lender on your behalf, so you can attend to your business recovery needs.

Determine Physical Damage and Engage Insurance

  • First, determine all of the physical items that need to be repaired. It’s critical to obtain multiple quotations.
  • If your repairs are extensive, you may want to hire an attorney who specializes in real estate, insurance and contracts. Critically, this attorney will work directly with the insurance adjuster.
  • On the advice of an attorney, you may want to hire your own “public adjuster”. A public adjuster works for you and not the insurance company.
  • Find out the procedures for paying for repairs. Some insurance companies have preferred providers. They may have their own forms and secure links for invoices.
  • If you were already considering renovations, consider combining hurricane repair with renovations. Click here for more information on this business plan.

Loss of Income or Business Interruption

  • In addition to physical damage, how is your business functioning?
  • Have you suffered business interruption because your business had to close due to damage or power failures?
  • Were you unable to operate at capacity because your employees were unavailable?
  • Make a list of all of the ways your business had economic injury. If you have business interruption insurance, you can provide this list to your agent.

Apply for SBA Disaster Loans

  • The Small Business Administration sets aside money in cases of major weather events.
  • In order to apply for help following Hurricane Milton, click here. For Hurricane Helene, click here.
  • You can receive low interest loans to cover uninsured losses, whether they are physical damage or economic injury.
  • GRP Capital can assist with applying for SBA help. Please contact our team to start the process.
Please let us know if you are interested in financing for any of your business projects. Any member of our GRP Capital team would be happy to help you.

Whether you are investing in your first commercial business or expanding your existing portfolio, our in-house experts can help you identify and close on the right loan for your financing needs.
Our primary mission is to provide the most responsive, client-oriented financial services by offering competitive commercial and real estate loan products through a chain of banking and non-banking networks.
Hurricane Texas picture

Combining Storm Damage Repairs and Renovation

Are you looking at storm damage repair from Hurricane Beryl?

Hurricane Beryl is now in the history books. This storm kicked off the traditional hurricane season and caused significant damage over a large swath of the country. Now, business owners are facing water damage as well as long-term power outages. Consequently, many business owners are working on their hurricane repair plans.

Sometimes storms come with a silver lining. This could be one of those times.

If you have a property that is in need of hurricane repairs, consider upgrading or renovating your property at the same time as the repairs. You could undertake more extensive renovations, even take on deferred maintenance. Especially if you have had any previous mold that needs to be remediated, using insurance proceeds to clean up water intrusion may allow you to fix both problems.

Actually, doing additional renovations during repairs can be very cost-effective. Your demolition costs may be lower. Your timeframe may be ideal, too. Essentially, you are combining your insurance compensation with other financing. GRP Capital can help secure financing through a new loan or a refinanced or restructured existing loan.

Preparing for Your Storm Damage Repair and Renovations

  • First, determine what needs to be repaired. It’s critical to obtain multiple quotations.
  • Find out the procedures for paying for repairs. Some insurance companies have preferred providers. They may have their own forms and secure links for invoices.
  • If your repairs are extensive, you may want to hire an attorney who specializes in real estate, insurance and contracts. Critically, this attorney will work directly with the insurance adjuster.
  • Now make a list of what items you would renovate if money were no object. Choose from projects that would enhance your property or increase its value. Consider franchise renovation packages if applicable.
  • Then rank your list of projects.
  • Next, talk with trusted construction and renovation professionals. Certainly, discuss both the critical hurricane repairs and your wishlist.
  • Finally, determine how much you would save by combining projects.

Contact GRP Capital while you are gathering your data. Be sure to let us know about your repairs and your wishlist. Truthfully not all lenders show interest in every kind of loan. Fortunately, we know which lenders in our lender network are financing these combination project loans. This knowledge can save you time and money.


Please let us know if you are interested in financing for any of your business projects. Any member of our GRP Capital team would be happy to help you.

Whether you are investing in your first commercial business or expanding your existing portfolio, our in-house experts can help you identify and close on the right loan for your financing needs.
Our primary mission is to provide the most responsive, client-oriented financial services by offering competitive commercial and real estate loan products through a chain of banking and non-banking networks.

Combining Hurricane Repair and Renovation

Hurricane Ian was a big storm, causing major damage. Consequently, many business owners are working on their hurricane repair plans.

Sometimes storms come with a silver lining. This could be one of those times.

If you have a property that is in need of hurricane repairs, consider upgrading your property at the same time. You can undertake more extensive renovations, even deferred maintenance.

Actually, doing additional renovations during repairs can be very cost-effective. Your demolition costs may be lower. Your timeframe may be ideal, too. Essentially, you are combining your insurance compensation with other financing. GRP Capital can help secure financing through a new loan or a refinanced or restructured existing loan.

Preparing for Your Hurricane Repair and Renovations

  • First, determine what needs to be repaired. It’s critical to obtain multiple quotations.
  • Find out the procedures for paying for repairs. Some insurance companies have preferred providers. They may have their own forms and secure links for invoices.
  • If your repairs are extensive, you may want to hire an attorney who specializes in real estate, insurance and contracts. Critically, this attorney will work directly with the insurance adjuster.
  • Now make a list of what items you would renovate if money were no object. Choose from projects that would enhance your property or increase its value. Consider franchise renovation packages if applicable.
  • Then rank your list of projects.
  • Next, talk with trusted construction and renovation professionals. Certainly, discuss both the critical hurricane repairs and your wishlist.
  • Finally, determine how much you would save by combining projects.

Contact GRP Capital while you are gathering your data. Be sure to let us know about your repairs and your wishlist. Truthfully not all lenders show interest in every kind of loan. Fortunately, we know which lenders in our lender network are financing these combination project loans. This knowledge can save you time and money.


Please let us know if you are interested in financing for any of your business projects. Any member of our GRP Capital team would be happy to help you.

Whether you are investing in your first commercial business or expanding your existing portfolio, our in-house experts can help you identify and close on the right loan for your financing needs.
Our primary mission is to provide the most responsive, client-oriented financial services by offering competitive commercial and real estate loan products through a chain of banking and non-banking networks.

Hospitality Loan Options

What is happening in the world of hospitality loan options? Which road should you take?

Are you looking to purchase an existing hotel? Or do you already own a property and are facing an upcoming loan maturity? Are you trying to figure out the timing of a refinance or considering remodeling or reflagging, rolling that into a refi?

Lenders have become more selective about hotel loans. In addition, borrowers have to contend with current high interest rates.

What are the best ways forward?

Different Loan Products to consider:

  • Conventional Loans: There are a few lenders who offer conventional loans, often at fixed prices. However, these loans are typically reserved for the highest echelon of hotels and for larger loan amounts. They also tend to require greater equity injections.
  • USDA Rural Hotel Loans: If your property is not in the heart of an urban area, you may be eligible for a USDA loan, designed to support businesses outside of cities. These loans often have variable interest rates but are adjusted infrequently (some as few as every five years).
  • SBA (Small Business Administration): SBA loans are in many cases the most affordable loan products for hospitality owners with properties of all types, from economy to luxury. Their variable rates mean that when interest rates do eventually go down, borrowers will benefit. In addition, GRP Capital has relationships with many preferred lenders, which decreases the time to close.
  • Bridge loans. Sometimes a transaction needs to occur quickly. This is especially true if the seller is courting multiple buyers and the first one in the gate gets the deal. Bridge lending offers a quick, temporary solution, but sometimes with a high short-term interest rate.

Special Considerations for Purchasing a New Hospitality Business:

• Does a New Purchase Fit into Your business plan? There are hospitality businesses that are for sale now. It could be that the seller is ready for a new project. Or it could be that the seller’s note is coming due and they, too, are weighing their own options. Talk to us about the range of interest rates that you could be paying for a new loan. Then determine if this is affordable. We highly recommend doing this before signing a PSA (Purchase Sale Agreement) or paying any earnest money.

• Determine the True Expenses of a New Business: New businesses have many expenses. We always critically review the seller’s financial statements with our clients. It’s important to understand which fixed costs buyers will be taking on and which costs were ones that will not recur. Of particular interest are the insurance costs, the labor costs, the franchise agreement (which we can give guidance on) and of course the actual cost of the loan.

If you would like to discuss hospitality loan options or any other business plans, feel free to contact our team.  We can conduct a business evaluation, reach out to our lenders, offer advice on bidding and secure financing for you. An initial business evaluation is complimentary.

Debt Coverage: How DSCR has Eclipsed LTV

Have you been hearing terms like debt coverage and DSCR more than ever before?

Did you already know about loan to value or LTV and are now wondering about this new alphabet soup?

Well, here is what is going on!

DSCR stands for Debt Service Coverage Ratio. It’s actually a very simple fraction. Your DSCR is your net operating income (NOI) divided by your annual debt payment. So, if your business netted $500,000 annually and you pay $400,000 yearly in mortgages and other long-term debt, your DSCR would be 1.25.

What to know about your Debt Coverage:

• What’s a good DSCR? “Good” DSCR figures can vary by industry and even location. In general, lenders are looking for a DSCR of at least 1.15. However, sometimes there are extenuating circumstances, like ongoing long-term renovation, buyouts of partners and other issues.

• Hey, I have a great LTV! We talk with our lending partners every day. Three or four years ago, the most important number in securing financing for our clients was the LTV or loan to value. This figure is a ratio that expresses the value of your property and business divided by the amount of the financing you are requesting. However, lenders are telling us now that they are not as concerned with LTV and are much more carefully eyeing DSCR!

• Why is DSCR as important or more important than LTV now?  Within the last several years, commercial real estate had been rising rapidly in all sectors from office space to hospitality to everything in between. But the changing economic climate has thrown disorder into many sectors. Lenders and appraisers have become much more conservative and are not assuming high valuations like they used to. Instead, they are looking at what is tangible and real: how much a business earns and how much it costs to pay for debt.

What happens if my DSCR is too low?  Sometimes a property’s debt service coverage ratio is below the lender’s minimum. At the same time, the client wants a loan at the upper limit of the LTV. When this happens, the lender will have to reduce the loan amount in order to maintain the minimum DSCR. This is referred to as the loan amount being debt service constrained.

• Business and Personal Cash Flow: Lenders of course evaluate your business DSCR. But they also evaluate your global cash flow. They add up the income from all of your businesses and determine your expenses, including debt payments, both business and personal.

Don’t Forget Your EIDL!

• EIDL is Debt:  If you had an EIDL (Economic Injury Disaster Loan), this shows up as debt on your balance sheet and is included in your DSCR calculations. Fortunately, the low rates on EIDL’s make the payments for them relatively affordable, but they do add to your indebtedness and affect the DSCR ratio.

• What happens to my previous EIDL’s if I’m selling, buying or refinancing? This varies depending on your debt coverage and your circumstances. To learn more about these issues, see this blog about EIDL‘s and new loan transactions.

If you are considering a loan for purchase or refinance or construction and would like to discuss your plans, feel free to contact our team.  We can conduct a business evaluation and even prequalify you for a loan at no cost to you. We will help you determine your DSCR and LTV and match you to appropriate lenders for your projects.

Business Evaluation: Call Us BEFORE You Bid

Why are we offering you a free business evaluation? Many clients are looking right now for the next project. Are you one of these people?

If so, we love to hear from clients who are ready to take on new challenges. These might include expanding current businesses or adding new projects to portfolios. However, we find we can be even more helpful to clients when they contact us even before bidding on a business or property.

Before You Make an Offer:

• Business Evaluation of the subject property: We can help evaluate the business. We examine the documents you have or with your permission, we can also contact the current owners. Then we begin to determine the business’ strengths and weaknesses. We provide an independent opinion on reasonable projections for expenses and revenues as well as advice on possible challenges.

• Understanding You as a Borrower: Our clients’ comfort and trust in our process is critical. In order to foster the very best relationships, we spend a lot of time getting to know our clients. We want to understand your business goals as well any concerns you might have. As a result, we will then know what your priorities are in terms of financing and finding the best loan products for you.

• Considering Hidden Costs You Might Not Have Considered:  We have the benefit of closing hundreds of loans. Therefore, we have experienced potential hiccups and can pass on that wisdom to you. We can offer information about whether a survey will be necessary, timely advice about insurance in your local marketplace or the willingness of lenders to fund your business proposal. Our experience and advice can save you time, money and frustration.

Free Prequalification:

• Getting to Know All of the Partners:  We will discuss your organizational structure and make sure it is set up in the best way to find an appropriate lender. Having this conversation before making a bid can prevent having to make changes in the ownership of businesses. It also allows for a free and honest conversation about what will be expected monetarily from each of the partners during the initial setup of the business.

• Choosing Guarantors: Not every partner should necessarily be a guarantor. We can guide you to select guarantors based upon the merits of your project.

• Review Personal Financial Statements: Again, we help all our clients to establish their own personal financial statement, which we then (as needed) share with potential lenders. This process helps us work together to determine what each client can afford and how to best show their personal assets and liabilities to greatest advantage.

If you would like to schedule your free business evaluation, contact Veeraj Patel, our Credit Analyst at 239.294.1664.

If you are considering a loan for purchase or refinance and would like to discuss your plans, feel free to contact our team.  We can conduct a business evaluation and even prequalify you for a loan at no cost to you.

Colorado hotel loan; repeat client buys nearby property

We were happy to close a Colorado hotel loan for a repeat client of ours. This partnership group has found success in the Mountain states. They were eyeing a property not too far from a successful hotel that they previously purchased with a GRP-supported loan. In addition, they discovered that there was an absentee owner. Savvy business owners often target businesses held by out-of-town owners as potential purchases. Often, these properties can be extracted for more revenue. In this case, our clients will be able to manage this hotel along with their other hotel, pooling staff and using similar operating procedures.

GRP Capital Managing Director  Krishan Patel led our team to close this loan. Patel stated, “I know this client group well, as we have closed loans with them before. They are excellent business owners and managers and know the hospitality industry very well, particularly the Colorado hotel business. We supported them through the challenges of purchasing from an out-of-state owner. Now they are ready to have even greater market penetration with their two nearby properties.”

Things to remember when purchasing from Absentee Landlords:

• Who knows this business the best? Out of state (or country) business owners vary in their ownership style. Some really understand all of the properties in their portfolio. Others defer to their management team and know very little. If you are considering purchasing from an absentee landlord, determine if they know their business well and if not, get the contact number of the person who does.

•  Determine property condition Again, depending on the style of the owner, properties without ownership nearby can have deferred maintenance issues. Utilize the appraiser or even your own third party hires to determine the property condition. Be sure to include any needed renovation or upgrades in your loan package, especially if completing these would lead to greater revenue.

•  Get a solid understanding of the financials Even before potential lenders underwrite the loan, you should have a good sense of how the business is doing. What are its challenges and strengths? What kind of management is needed? Most importantly, will you be able to give the attention and oversight needed to make this business profitable?

Our GRP Capital team specializes in finding the right lender for each project. We save our clients time and money, as we research  the best choices for their funding sources. Our experience allows our clients to find funding that is project-appropriate and will allow for sufficient cash flow. If you are considering becoming a first-time (or second or third time!) buyer, we can assist you.

Baton Rouge bridge over river

Refinanced hotel in Louisiana: Timing a Refi

We recently closed a loan for a refinanced hotel. Our Louisiana clients own a profitable, healthy hotel. They purchased it as less experienced buyers, relying on a seller note at the time. Now they were ready to refinance this seller note. They had developed their management resumes and built up their credit. So they approached Senior Associate Ryan Dumas for advice and support.

Ryan Dumas worked with the clients to determine if now was the best time for a refinanced hotel loan. He understood their goals and their business vision. The clients wanted to have a more traditional loan and they wanted to disentangle themselves from the seller. Ryan stated, “We successfully closed this refinanced hotel loan. Their new loan is secure and guaranteed. Now my clients have a bank as a lender and not somebody from the community. They no longer have a lender relationship with the seller; they are just neighbors and colleagues.”

Is Now the Time for a Refinanced Hotel?

• Is your current note maturing? We receive many loan inquiries when current mortgages are maturing. As a note matures, either the entire balance has to be paid off or the loan has to be somehow modified or extended. Maturing notes require negotiation. For many business owners, a pending note maturity is a great date to refinance.

• Can you lower your mortgage payments or pay off your mortgage more quickly?  It is easy to determine if you can save money with a refinance. When we seek out loan offers from our network of lenders, they will provide the terms. These terms will dictate your monthly payments and how long it will take to pay off your loan. You can then determine what the best business decision is. There are closing costs associated with all loans. As a result, you will need to consider how long it will take for your lower payments to offset those costs.

• Are you looking to change your lender? Some clients are interested in developing a new business relationship with a prospective lender. Other clients, like our Louisiana ones, simply wanted to extricate themselves from a loan that felt a little too personal. This can be the case with private notes, especially ones that are held by family or community members.

Our GRP Capital team specializes in finding the right lender for each project. We save our clients time and money, as we research the best choices for their funding sources. Our experience allows our clients to find funding that is project-appropriate and will allow for sufficient cash flow. Whether you are looking to refinance or purchase, we would love to discuss your business plans with you. If you are considering becoming a first-time (or second or third time!) buyer, we can assist you.

Texas RV Park Purchase and Upgrade

GRP Capital is pleased to announce a new loan for the purchase and upgrade of an RV park. This facility is located in Southeast Texas.

Our GRP Capital team worked closely with his client, helping to facilitate the financing. Managing Director Krishan Patel said, “The borrowers were great to work with. They are experienced in this sector. With this purchase, we are helping them expand their portfolio. Our entire GRP Capital team consulted with the clients. We worked diligently to steer them towards a loan that matched their financing needs. Even better, we are making plans for the clients’ next acquisition.”

Why an RV Park is a Great Investment:

• Current Travel Trends: Tourism trends in the United State are favorable for RV park usage. Americans are favoring driving over flying and are anxious to arrive at far-flung destinations.

• Pandemic-Proof: Travel in a recreational vehicle or camper and lodging at an RV park make sense during our new normal. An RV park allows for sociability outside, while protecting vulnerable people from overexposure.

•  More opportunities for market penetration : While there are multiple hotels at many highway exits, this sector is not as crowded. An RV park with updated amenities can capture market share. This requires effective marketing, excellent management and maintenance and good decisions on what amenities drive occupancy.

•  Lenders Like RV Parks : Lenders, particularly SBA lenders, look favorably on this sector of hospitality lending. As a result, GRP Capital can find matches for qualified borrowers.

Our GRP Capital team specializes in finding the right lender for each project. We save our clients time and money, as we research  the best choices for their funding sources. Our experience allows our clients to find funding that is project-appropriate and will allow for sufficient cash flow. If you are considering becoming a first-time (or second or third time!) buyer, we can assist you.

Texas Hotel Owner Closes High Leverage Loan

Our clients already owned a Texas hotel. They were ready to purchase another Texas hotel in the northwest part of the state.

They really wanted to minimize their equity injection.

Each of our clients have different needs. Some are more rate-sensitive, some clients want loans with lenders who will become their primary business relationship. And some, like these clients, are looking for a high leverage loan.

Our GRP Capital Team worked closely with the clients. Managing Director Krishan Patel noted that he was proud of the sensitive guidance during the negotiations of the purchase and sale agreement. He also helped his clients prioritize the aspects of the new loan that were most important to them. “I was pleased that we were able to match these clients with a loan that met their needs. They have great experience in the hospitality industry. As a result, they will maximize the profit of their new hotel. Their ability to keep their equity injection manageable was a critical component of the loan. I look forward to working on other projects with them, as I know their situation and goals well.”

Best Practices for Organizing Your Equity Injection:

During underwriting, the clients worked quickly to provide evidence of their equity injection. The equity injection is the “money down”. If you are contemplating a new loan (not a refinance), here are some tips regarding equity injections.

• Sufficient equity: The lender will require bank statements or statements from stock accounts. These statements must show enough money. Just before closing, clients transfer these funds via wire.

• Dividing it Up: Typically, all of the partners participate in putting money down. Ideally, the equity injection is divided up proportionally among the partners. Most buyers contribute towards the down payment, matching the percentages of ownership.

•  Clean sources of equity : Down payments need to consist of funds that are “clean”. This means that the money has not been recently loaned to you. As you are choosing which accounts will be the source of your equity injection, choose wisely. The lender will “source” any large movements of money into an account (typically more than $1,000). This means you will have to tell the lender where the money came from and often provide a statement (or several) from the source of the transfer.

Our GRP Capital team specializes in finding the right lender for each project. We save our clients time and money, as we research  the best choices for their funding sources. Our experience allows our clients to find funding that is project-appropriate and will allow for sufficient cash flow. If you are considering becoming a first-time (or second or third time!) buyer, we can assist you.