Category Archives: Small Business

Making Your Financial Reports Work for You

Do your financial reports work for you?

Tax Day is behind us and either you have filed your taxes or have filed an extension. Now is the perfect time to look more closely at your financial reports.

Ask yourself these questions:

  • Are your financial reports giving you a true picture of your businesses?
  • Are they a useful tool?
  • Do you receive these reports in a timely fashion?

Consider making these changes to improve your financial reports:

• Produce reports more often. If your CPA only creates financial reports for you taxes, then you aren’t regularly receiving financial reports. Make the change and allocate the funds right now for at least quarterly reports and insist on receiving your quarterly reports within 30 days of the end of the quarter. (You can make exceptions to accommodate for your accountant’s tax preparation schedule.) If you are looking for financing, you may need monthly reports. If this is the case, again, let your CPA know.

Balance Sheets are a critical part of financial reporting. Financial reports have two components: profit and loss statements as well as balance sheets. Balance sheets should clearly list your assets and also your liabilities, including any EIDL (Economic Injury Disaster Loans). If you would like more information about dealing with current EIDL loans in future financing arrangements, click here.

Create your own business debt schedule. Whenever you are looking for financing, the lenders will ask for your business debt schedule. To make sure your balance sheets are accurate, try to fill out a business debt schedule ahead of time. We can provide you with a typical form if you want to try this exercise.

Make sure your P&L is complete and accurate. If you produce your own financial statements, then you can merge your payroll and electronic bill payments into your reporting. Then, more aspects of your business are included. If your accountant is producing your reports, now is a good time to set up a meeting to discuss your reports and making them work for you by being more complete.

If you are considering a loan for purchase or refinance or construction and would like to discuss your plans, feel free to contact our team.  We can conduct a business evaluation and even prequalify you for a loan at no cost to you.
signing documents like title insurance

Title Insurance: What do I Need to Know?

Have you heard the one about the friend who couldn’t close his loan, because but there was an issue with title insurance? Don’t be that friend!

All lenders require Title Insurance.

FAQs about Title Insurance:

• Who benefits from title insurance? Well, it depends. Lender’s title insurance protects the lender and owner’s title insurance works for the borrower.

What’s the difference? Lender’s title insurance is mandatory and owner’s title insurance is often optional. We recommend always purchasing the Owner’s Title Policy. This is not a place to save money.

What is the purpose of title insurance? Title insurance ensures that the borrower has the clear ownership of the property. Additionally, title insurance also protects the lender by ensuring their claim on the property if they are not repaid for the loan.

What could possibly go wrong with the title?

We have seen many issues that make title complicated. We call issues with title a “cloud on title”. Title agents are always looking for “clear title”. Things that cloud a title could include:

  • errors in the survey
  • boundary disputes
  • liens placed on the property (before you even purchased it)
  • old tax liabilities
  • improper settling of estates after a death or divorce
  • Previous EIDL loans

What is the process of obtaining title insurance?  Your title agent will run a preliminary title report on any property you are financing. Then, they will see if there are any claims on the property. Afterwards, the title officer then has to remove anything that would cloud title. Sometimes, there are things the seller has to do. As you can see, title issues can be complicated. Thus it is critical to hire a competent attorney to advise you when engaging in financing loans.

How do borrowers pay for title insurance? Title insurance is based upon the value of the loan. Every year, the lender renews their title insurance and this cost is included in your loan. The price lowers each year as the loan is paid off. Borrowers only pay for Owner’s insurance once, at closing.

If you are considering a loan for purchase or refinance or construction and would like to discuss your plans, feel free to contact our team.  We can conduct a business evaluation and even prequalify you for a loan at no cost to you. We will help you determine your DSCR and LTV and match you to appropriate lenders for your projects.
Debt Coverage: How DSCR has Eclipsed LTV

Have you been hearing terms like debt coverage and DSCR more than ever before?

Did you already know about loan to value or LTV and are now wondering about this new alphabet soup?

Well, here is what is going on!

DSCR stands for Debt Service Coverage Ratio. It’s actually a very simple fraction. Your DSCR is your net operating income (NOI) divided by your annual debt payment. So, if your business netted $500,000 annually and you pay $400,000 yearly in mortgages and other long-term debt, your DSCR would be 1.25.

What to know about your Debt Coverage:

• What’s a good DSCR? “Good” DSCR figures can vary by industry and even location. In general, lenders are looking for a DSCR of at least 1.15. However, sometimes there are extenuating circumstances, like ongoing long-term renovation, buyouts of partners and other issues.

Hey, I have a great LTV! We talk with our lending partners every day. Three or four years ago, the most important number in securing financing for our clients was the LTV or loan to value. This figure is a ratio that expresses the value of your property and business divided by the amount of the financing you are requesting. However, lenders are telling us now that they are not as concerned with LTV and are much more carefully eyeing DSCR!

• Why is DSCR as important or more important than LTV now?  Within the last several years, commercial real estate had been rising rapidly in all sectors from office space to hospitality to everything in between. But the changing economic climate has thrown disorder into many sectors. Lenders and appraisers have become much more conservative and are not assuming high valuations like they used to. Instead, they are looking at what is tangible and real: how much a business earns and how much it costs to pay for debt.

What happens if my DSCR is too low?  Sometimes a property’s debt service coverage ratio is below the lender’s minimum. At the same time, the client wants a loan at the upper limit of the LTV. When this happens, the lender will have to reduce the loan amount in order to maintain the minimum DSCR. This is referred to as the loan amount being debt service constrained.

Business and Personal Cash Flow: Lenders of course evaluate your business DSCR. But they also evaluate your global cash flow. They add up the income from all of your businesses and determine your expenses, including debt payments, both business and personal.

Don’t Forget Your EIDL!

• EIDL is Debt:  If you had an EIDL (Economic Injury Disaster Loan), this shows up as debt on your balance sheet and is included in your DSCR calculations. Fortunately, the low rates on EIDL’s make the payments for them relatively affordable, but they do add to your indebtedness and affect the DSCR ratio.

What happens to my previous EIDL’s if I’m selling, buying or refinancing? This varies depending on your debt coverage and your circumstances. To learn more about these issues, see this blog about EIDL‘s and new loan transactions.

If you are considering a loan for purchase or refinance or construction and would like to discuss your plans, feel free to contact our team.  We can conduct a business evaluation and even prequalify you for a loan at no cost to you. We will help you determine your DSCR and LTV and match you to appropriate lenders for your projects.
Business Evaluation: Call Us BEFORE You Bid

Why are we offering you a free business evaluation? Many clients are looking right now for the next project. Are you one of these people?

If so, we love to hear from clients who are ready to take on new challenges. These might include expanding current businesses or adding new projects to portfolios. However, we find we can be even more helpful to clients when they contact us even before bidding on a business or property.

Before You Make an Offer:

• Business Evaluation of the subject property: We can help evaluate the business. We examine the documents you have or with your permission, we can also contact the current owners. Then we begin to determine the business’ strengths and weaknesses. We provide an independent opinion on reasonable projections for expenses and revenues as well as advice on possible challenges.

Understanding You as a Borrower: Our clients’ comfort and trust in our process is critical. In order to foster the very best relationships, we spend a lot of time getting to know our clients. We want to understand your business goals as well any concerns you might have. As a result, we will then know what your priorities are in terms of financing and finding the best loan products for you.

• Considering Hidden Costs You Might Not Have Considered:  We have the benefit of closing hundreds of loans. Therefore, we have experienced potential hiccups and can pass on that wisdom to you. We can offer information about whether a survey will be necessary, timely advice about insurance in your local marketplace or the willingness of lenders to fund your business proposal. Our experience and advice can save you time, money and frustration.

Free Prequalification:

• Getting to Know All of the Partners:  We will discuss your organizational structure and make sure it is set up in the best way to find an appropriate lender. Having this conversation before making a bid can prevent having to make changes in the ownership of businesses. It also allows for a free and honest conversation about what will be expected monetarily from each of the partners during the initial setup of the business.

Choosing Guarantors: Not every partner should necessarily be a guarantor. We can guide you to select guarantors based upon the merits of your project.

Review Personal Financial Statements: Again, we help all our clients to establish their own personal financial statement, which we then (as needed) share with potential lenders. This process helps us work together to determine what each client can afford and how to best show their personal assets and liabilities to greatest advantage.

If you would like to schedule your free business evaluation, contact Veeraj Patel, our Credit Analyst at 239.294.1664.

If you are considering a loan for purchase or refinance and would like to discuss your plans, feel free to contact our team.  We can conduct a business evaluation and even prequalify you for a loan at no cost to you.
Colorado hotel loan; repeat client buys nearby property

We were happy to close a Colorado hotel loan for a repeat client of ours. This partnership group has found success in the Mountain states. They were eyeing a property not too far from a successful hotel that they previously purchased with a GRP-supported loan. In addition, they discovered that there was an absentee owner. Savvy business owners often target businesses held by out-of-town owners as potential purchases. Often, these properties can be extracted for more revenue. In this case, our clients will be able to manage this hotel along with their other hotel, pooling staff and using similar operating procedures.

GRP Capital Managing Director  Krishan Patel led our team to close this loan. Patel stated, “I know this client group well, as we have closed loans with them before. They are excellent business owners and managers and know the hospitality industry very well, particularly the Colorado hotel business. We supported them through the challenges of purchasing from an out-of-state owner. Now they are ready to have even greater market penetration with their two nearby properties.”

Things to remember when purchasing from Absentee Landlords:

• Who knows this business the best? Out of state (or country) business owners vary in their ownership style. Some really understand all of the properties in their portfolio. Others defer to their management team and know very little. If you are considering purchasing from an absentee landlord, determine if they know their business well and if not, get the contact number of the person who does.

•  Determine property condition Again, depending on the style of the owner, properties without ownership nearby can have deferred maintenance issues. Utilize the appraiser or even your own third party hires to determine the property condition. Be sure to include any needed renovation or upgrades in your loan package, especially if completing these would lead to greater revenue.

•  Get a solid understanding of the financials Even before potential lenders underwrite the loan, you should have a good sense of how the business is doing. What are its challenges and strengths? What kind of management is needed? Most importantly, will you be able to give the attention and oversight needed to make this business profitable?

Our GRP Capital team specializes in finding the right lender for each project. We save our clients time and money, as we research  the best choices for their funding sources. Our experience allows our clients to find funding that is project-appropriate and will allow for sufficient cash flow. If you are considering becoming a first-time (or second or third time!) buyer, we can assist you.

Self Storage Units are Strong Investments

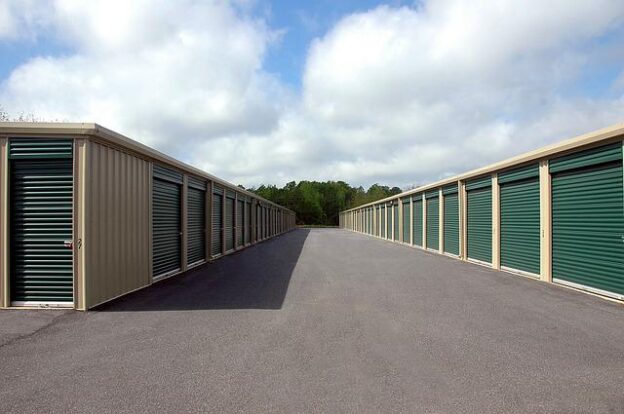
A self storage loan may be a good fit for you and your business portfolio. What are some reasons that lenders are eager to fund purchases, refinances and even construction projects for self storage? We have even been successful getting cash out with a recent refinance.

A Self Storage Loan is a great bet right now.

• Self Storage facilities tend to be easy to maintain. Unlike homes and other businesses with more complex infrastructure, self storage facilities are designed for stuff and not people. There is limited water onsite. There may be a mix of temperature controlled units and those without. Even the electricity can be very minimal in these units, typically to prevent renters from doing projects onsite and spending too much time onsite. The most critical components of maintenance are typically security and lighting.

People need storage during lifetime transitions.  Most people need some sort of storage options at some point. Whether customers are downsizing, moving to retirement communities, taking over the belongings of a loved one or changing locations for any reason, changing jobs or moving in and out of university settings, self storage is an affordable short term solution. Therefore, every community needs storage options of a variety of sizes and types.

• People store for longer than they anticipate. Storage customers typically rent as a stopgap measure. However, they tend to underestimate how long they will require storage. In addition, storage is so easy and the prices can be quite competitive. As a result, short term solutions often become long term patterns. This is great for owners!

Self Storage Upgrades:

If you already own a storage business or are looking to purchase one, there are some key upgrades that add value to the company:

  • Setting up automated security. Security is one of the key expenses and the most important amenity for most renters. Gate security and onsite cameras protect your investment and make your renters feel safer.
  • Enabling features that facilitate timely payments: There are excellent platforms that remind customers by text and email of upcoming payments, utilize an app to make payments and help customers set up automatic payments. These features increase on-time payments and do not require staff intervention to track down regular on-time renters.
  • Climate control. Depending on the marketplace, there may be a demand for a certain mix of climate control units. Upmarket storage may also include humidity control, even more secure locations and special units for vehicles.

Our GRP Capital team specializes in finding the right lender for each project. We save our clients time and money, as we research the best choices for their funding sources. Our experience allows our clients to find funding that is project-appropriate and will allow for sufficient cash flow. Whether you are looking to refinance or purchase, we would love to discuss your business plans with you. If you are considering becoming a first-time (or second or third time!) buyer, we can assist you.

Self Storage Loan Closes; Cash Out Too!

Congratulations to our Texas client who recently refinanced his self storage loan. He worked closely with Senior Associate Ryan Dumas and the rest of our team.

Ryan Dumas enjoyed getting to know our client, who managed to fit in getting us documents quickly, despite a very busy work schedule. Ryan noted, “I was very pleased that we found a great match for this self storage loan using our lender network. We found a competitive loan with fixed rates for a ten year note. My client got a decent amount of cash out, just from the terms of the loan. But even better, when the appraisal results came in and they were so favorable, we worked with the lender and got even more cash out! My client has lots of plans to continue to maintain this business and preserve his profitability. ”

A Self Storage Loan is a great bet right now. Why?

• Self Storage facilities tend to be easy to maintain. Unlike homes and other businesses with more complex headquarters, self storage facilities are designed for stuff and not people. There is limited water onsite. There may be a mix of temperature controlled units and those without. Even the electricity can be very minimal in these units. The most critical components of maintenance are typically security and lighting.

People need storage during lifetime transitions.  Most people need some sort of storage options at some point during their live. Whether customers are downsizing, moving to retirement communities, taking over the belongings of a loved one or changing locations for any reason, changing jobs or moving in and out of university settings, self storage is an affordable short term solution. Therefore, every community needs storage options of a variety of sizes and types.

• People store for longer than they anticipate. Storage customers typically rent as a stopgap measure. However, they tend to underestimate how long they will require storage. In addition, storage is so easy and the prices can be quite competitive. As a result, short term solutions often become long term patterns. This is great for owners!

Our GRP Capital team specializes in finding the right lender for each project. We save our clients time and money, as we research the best choices for their funding sources. Our experience allows our clients to find funding that is project-appropriate and will allow for sufficient cash flow. Whether you are looking to refinance or purchase, we would love to discuss your business plans with you. If you are considering becoming a first-time (or second or third time!) buyer, we can assist you.

Baton Rouge bridge over river

Refinanced hotel in Louisiana: Timing a Refi

We recently closed a loan for a refinanced hotel. Our Louisiana clients own a profitable, healthy hotel. They purchased it as less experienced buyers, relying on a seller note at the time. Now they were ready to refinance this seller note. They had developed their management resumes and built up their credit. So they approached Senior Associate Ryan Dumas for advice and support.

Ryan Dumas worked with the clients to determine if now was the best time for a refinanced hotel loan. He understood their goals and their business vision. The clients wanted to have a more traditional loan and they wanted to disentangle themselves from the seller. Ryan stated, “We successfully closed this refinanced hotel loan. Their new loan is secure and guaranteed. Now my clients have a bank as a lender and not somebody from the community. They no longer have a lender relationship with the seller; they are just neighbors and colleagues.”

Is Now the Time for a Refinanced Hotel?

• Is your current note maturing? We receive many loan inquiries when current mortgages are maturing. As a note matures, either the entire balance has to be paid off or the loan has to be somehow modified or extended. Maturing notes require negotiation. For many business owners, a pending note maturity is a great date to refinance.

Can you lower your mortgage payments or pay off your mortgage more quickly?  It is easy to determine if you can save money with a refinance. When we seek out loan offers from our network of lenders, they will provide the terms. These terms will dictate your monthly payments and how long it will take to pay off your loan. You can then determine what the best business decision is. There are closing costs associated with all loans. As a result, you will need to consider how long it will take for your lower payments to offset those costs.

• Are you looking to change your lender? Some clients are interested in developing a new business relationship with a prospective lender. Other clients, like our Louisiana ones, simply wanted to extricate themselves from a loan that felt a little too personal. This can be the case with private notes, especially ones that are held by family or community members.

Our GRP Capital team specializes in finding the right lender for each project. We save our clients time and money, as we research the best choices for their funding sources. Our experience allows our clients to find funding that is project-appropriate and will allow for sufficient cash flow. Whether you are looking to refinance or purchase, we would love to discuss your business plans with you. If you are considering becoming a first-time (or second or third time!) buyer, we can assist you.

Texas RV Park Purchase and Upgrade

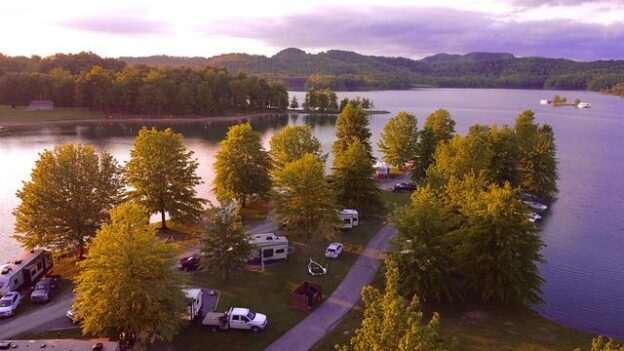
GRP Capital is pleased to announce a new loan for the purchase and upgrade of an RV park. This facility is located in Southeast Texas.

Our GRP Capital team worked closely with his client, helping to facilitate the financing. Managing Director Krishan Patel said, “The borrowers were great to work with. They are experienced in this sector. With this purchase, we are helping them expand their portfolio. Our entire GRP Capital team consulted with the clients. We worked diligently to steer them towards a loan that matched their financing needs. Even better, we are making plans for the clients’ next acquisition.”

Why an RV Park is a Great Investment:

• Current Travel Trends: Tourism trends in the United State are favorable for RV park usage. Americans are favoring driving over flying and are anxious to arrive at far-flung destinations.

Pandemic-Proof: Travel in a recreational vehicle or camper and lodging at an RV park make sense during our new normal. An RV park allows for sociability outside, while protecting vulnerable people from overexposure.

•  More opportunities for market penetration : While there are multiple hotels at many highway exits, this sector is not as crowded. An RV park with updated amenities can capture market share. This requires effective marketing, excellent management and maintenance and good decisions on what amenities drive occupancy.

•  Lenders Like RV Parks : Lenders, particularly SBA lenders, look favorably on this sector of hospitality lending. As a result, GRP Capital can find matches for qualified borrowers.

Our GRP Capital team specializes in finding the right lender for each project. We save our clients time and money, as we research  the best choices for their funding sources. Our experience allows our clients to find funding that is project-appropriate and will allow for sufficient cash flow. If you are considering becoming a first-time (or second or third time!) buyer, we can assist you.

Texas Hotel Owner Closes High Leverage Loan

Our clients already owned a Texas hotel. They were ready to purchase another Texas hotel in the northwest part of the state.

They really wanted to minimize their equity injection.

Each of our clients have different needs. Some are more rate-sensitive, some clients want loans with lenders who will become their primary business relationship. And some, like these clients, are looking for a high leverage loan.

Our GRP Capital Team worked closely with the clients. Managing Director Krishan Patel noted that he was proud of the sensitive guidance during the negotiations of the purchase and sale agreement. He also helped his clients prioritize the aspects of the new loan that were most important to them. “I was pleased that we were able to match these clients with a loan that met their needs. They have great experience in the hospitality industry. As a result, they will maximize the profit of their new hotel. Their ability to keep their equity injection manageable was a critical component of the loan. I look forward to working on other projects with them, as I know their situation and goals well.”

Best Practices for Organizing Your Equity Injection:

During underwriting, the clients worked quickly to provide evidence of their equity injection. The equity injection is the “money down”. If you are contemplating a new loan (not a refinance), here are some tips regarding equity injections.

• Sufficient equity: The lender will require bank statements or statements from stock accounts. These statements must show enough money. Just before closing, clients transfer these funds via wire.

Dividing it Up: Typically, all of the partners participate in putting money down. Ideally, the equity injection is divided up proportionally among the partners. Most buyers contribute towards the down payment, matching the percentages of ownership.

•  Clean sources of equity : Down payments need to consist of funds that are “clean”. This means that the money has not been recently loaned to you. As you are choosing which accounts will be the source of your equity injection, choose wisely. The lender will “source” any large movements of money into an account (typically more than $1,000). This means you will have to tell the lender where the money came from and often provide a statement (or several) from the source of the transfer.

Our GRP Capital team specializes in finding the right lender for each project. We save our clients time and money, as we research  the best choices for their funding sources. Our experience allows our clients to find funding that is project-appropriate and will allow for sufficient cash flow. If you are considering becoming a first-time (or second or third time!) buyer, we can assist you.