Category Archives: Consulting & Planning

EIDL Loans: What to know if you are buying, selling or refinancing

EIDL Loans (Economic Injury Disaster Loans offered by the Small Business Association) have helped many small business owners during the COVID pandemic. These low interest loans gave needed relief to some of the hardest hit industries, including hospitality.

Many business owners have EIDL Loans on the books. What do you need to know? What do you need to do? An EIDL has an impact on selling, buying and refinancing.

I’m Buying or Selling a Business with an EIDL Loan:

• All liens have to be released: Any lender who is funding the purchase of a business with real estate will require that buyers own the property “free and clear”. This means that there cannot be any liens (claims from lenders) on the property or the business. So, sellers must pay off previous EIDL loans be paid off prior to or at closing. Also, previous PPP (Paycheck Protection Program loans) will need to be have been forgiven.

• Perhaps One Exception:  Sellers may have multiple businesses or properties. If the EIDL is for the parent business, the new lender may find a way to make an exception.

Paying off an EIDL:  Be aware that the SBA does not accept payoff via wire. At closing the title or escrow company will have to make out a check for the balance of the EIDL. The borrower can find the balance on their SBA portal. The SBA website also has instructions for paying off the loan via mail.

I Have an EIDL and I want to Refinance

• Size matters!  If your EIDL loan is small, then the lender may agree to pay it off. They will roll the remainder of the EIDL into the total loan value. If the loan is larger, there are a few possibilities.

• Paying off an EIDL: You may be holding on to the proceeds of the loan (and therefore have cash on hand). However, a large EIDL may negatively impact your debt to income ratio. The lender may consider that you have too much debt and require you to pay off or pay down the loan.

• Subordinating an EIDL: Often lenders will agree to subordinate an EIDL. This means that they will request permission from the SBA to delay receiving payments for the EIDL until the mortgage has been paid off. Borrowers have to officially request subordination and the SBA has to grant it. This process is not automatic. In addition, requesting subordination can take some time. We have found that subordination happens most easily when we work with our network of SBA preferred lending partners.

I Have Other Businesses with EIDL loans:

The lender will underwrite your entire file and look at your affiliate businesses. If your businesses are cash flowing and covering your debts, there are no issues with other EIDL loans.

If you are considering a loan for purchase or refinance and would like to discuss your plans,  feel free to contact our team.  We have a network of lenders and can find the best match for your funding needs, saving you time and money, so you can focus on running your business.
Finding Loans for Self Storage

Self storage continues to be a good business with strong profits and room for growth. As a result, many lenders are eager to fund purchase, refinances and construction loans in the self storage industry.

Why are Self Storage Loans Great Opportunities?

• Steady Demand: Did you know that 10.6% of households currently rent storage units, according to Spare Foot? These renters need this product because of housing transitions, moving into places that lack sufficient storage. In addition, renters run the age gamut, from college graduates to those moving into senior living situations.

• Recession Proof: Storage demand has remained consistent. People need storage  when housing prices go up and when housing prices go down,

• Strong Return on Investment: Self storage properties have posted high ROI, higher than other real estate classes.

• Attractive to Lenders: Lenders like storage businesses for their profit potential, their lower maintenance costs and the ease in which owners can release units when renters have quite paying.

GRP Capital has a large network of lenders, many of whom have demonstrated interest in loans for the storage industry. We can help match our best lenders to your specific needs.

If you are interested in any form of self storage loans, now is the time to act. GRP Capital Business Associate Shail Madhav is ready to discuss your plans and funding needs right now, so you can take advantage of current low rates and lender interest. All consultations are free and GRP Capital never charges fees to borrowers. 

Read more about other aspects of finding funding in today’s climate here:

Becoming a Better Borrower

What Businesses do Lenders Like Now?

Deferred Maintenance: Planning and Setting Up a Capital Fund

Deferred maintenance: projects to keep up your commercial property that still have not been completed. It’s time to recommit to making your property look excellent and perform in peak condition.

Do you have deferred maintenance projects? What’s the best path forwards?

How to Make a Plan for Deferred Maintenance:

• First of all, understand your motivation: A property that is in good working order, that looks good cosmetically and operates appropriately reflects well on you as a business owner. This is important if you are ever looking to refinance or sell. In addition, guests and customers notice when their environment is looking tired. This affects word of mouth reputation about your business and can even show up in online reviews.

• Deferred maintenance may be allowing small problems to get worse: If you have experienced, for instance, small water damage and were just waiting for the right time to tackle these repairs, stop delaying. Appraisers and customers can easily spot water damage and it is an obvious sign of neglect. Further, water damage can cause serious issues beyond cosmetic ones.

• Consider Other Upgrades: Change out plumbing and fixtures, upgrade furniture and replace soft packages (linens, bedding, curtains) as well as larger, more extensive renovations.

• Create a detailed plan: First ask yourself if money were no object, what you would do to improve your property. Then figure out which of these items you can afford and which items retain or add the most value. Next, determine how long each project would last.

• Prioritize and Act: Create a calendar with all scheduled future maintenance, keeping notes on the budget and the timeline to complete each component. You know your property best. Work around its high and low seasons to determine the best timeline. Line up your contractors and workers and get to work!

Secure Good Advice: 

• Consult your franchise service director, if applicable.  Your franchise representative (if you have one) will help you prioritize and will understand what other business owners like you face. Ask for a site visit.  Specifically ask which projects have the greatest return on capital.

• Confer with your network. Arrange for a trusted owner of a business like yours for their advice.

• Contact GRP Capital.  We are happy to look at your financial statements and discuss what your business needs are. We can help you determine some of the best options to go forward.

Building Funds for CapEx and Utilizing them:

If you were in the position to have a Capital Expenditures (CapEx) fund prior to the pandemic, it’s time to start spending that fund. While you may have been focusing only on debt service and minimizing operating expenses from 2020 until now, you can now change gears.

If you have never set aside monies for CapEx, start now. We recommend designating 4% of your budget for CapEx. Further, we recommend setting aside money in a segregated fund, so that you can build up this nest egg and use it. These funds will be included in your balance sheet as an asset until you spend it.

If you are considering a loan for purchase or refinance and would like to discuss your plans for project maintenance or developing a CapEx budget and timeline, feel free to contact our team.  

Property Maintenance: Maintaining Your Brand

Property maintenance is important for a number of reasons. If you have been deferring maintenance to focus on operations, to keep costs down during the recent economic uncertainty, act now! It’s time to recommit to making your property look excellent and perform in peak condition.

What’s so Important About Property Maintenance:

• Maintaining Your Property is Maintaining Your Brand: A property that is in good working order, that looks good cosmetically and operates appropriately reflects well on you as a business owner. This is important if you are ever looking to refinance or sell. In addition, guests and customers notice when their environment is looking tired. This affects word of mouth reputation about your business and can even show up in online reviews.

• Deferred maintenance may be allowing small problems to get worse: If you have experienced small water damage and were just waiting for the right time to tackle these repairs, stop delaying. Appraisers and customers can easily spot water damage and it is an obvious sign of neglect. Further, water damage can cause serious issues beyond cosmetic ones.

Other maintenance issues to consider include changing out plumbing and fixtures, upgrading furniture and soft packages (linens, bedding, curtains) as well as larger, more extensive renovations.

How Should You Choose Which Deferred Maintenance to Do First?

• Consult your franchise service director, if applicable Request a site visit. Seek the knowledge and mentorship that these organizations provide. Ask for help in prioritizing projects, determining what improves your property the most and increases your appraised value. Specifically ask which projects have the greatest return on capital.

• Create a detailed plan: First ask yourself if money were no object, what you would do to improve your property. Then figure out which of these items you can afford and which items retain or add the most value. Next, determine how long each project would last.

• Prioritize and Act: Create a calendar with all scheduled future maintenance, keeping notes on the budget and the timeline to complete each component. You know your property best. Work around its high and low seasons to determine the best timeline. Line up your contractors and workers and get to work!

Building Funds for CapEx and Utilizing them:

If you were in the position to have a Capital Expenditures (CapEx) fund prior to the pandemic, it’s time to start spending that fund. While you may have been focusing only on debt service and minimizing operating expenses, you can now change gears.

If you have never set aside monies for CapEx, start now. We recommend designating 4% of your budget for CapEx. Further, we recommend setting aside money in a segregated fund, so that you can build up this nest egg and use it. These funds will be included in your balance sheet as an asset until you spend it.

If you are considering a loan for purchase or refinance and would like to discuss your plans for project maintenance or developing a CapEx budget and timeline, feel free to contact our team.  

Getting Ready to Borrow? Do These Now!

Are you getting ready to borrow money? With continuing low interest rates, now is an ideal time to start or grow an existing business.

We at GRP Capital guide our clients from the germ of a business idea to receipt of funds.

Many clients come to us with good business plans and even sufficient equity and/or debt coverage. But many clients neglect what we call due diligence. Due diligence is really understanding and researching the elements necessary to close the loan. Due diligence also means engaging professionals who will advise and serve your interests.

How You Can Be Ready To Borrow:

• Hire your own attorney:  An attorney, hired by you, can examine your purchase agreements, loan documents, and the title commitment letter and policies. A qualified attorney will protect you and your business interests and can even negotiate on your behalf. Borrowers are not always required to hire an attorney; however, we do not advise trying to save money by NOT hiring an attorney.

• Ask about previous environmental reports:  Typically, when a bank loans money, they will arrange for various site visits and reports. If you are looking at buying a business or if you are refinancing, the lender will require previous environmental reports and will also engage an appraisal. If the property never had an environmental report (maybe the private lender didn’t require it), you need to be sure that nothing adverse will be revealed. Always ask owners to see their ESA (environmental site assessments). This will ensure that you know about any issues with the property. Of particular concern are nearby gas stations and automobile repair shops.

• Look into title work and previous surveys: Not every property has a recent survey on file. Nowadays, most lenders are requiring updated surveys. Engaging a surveyor and obtaining the survey can take 4 weeks. Shortening the time frame comes with a surcharge. So if you are refinancing and don’t have a survey on hand, you will probably need to engage one. If you’re purchasing a business which includes real estate, as soon as you receive a letter of intent from the lender, you should consider engaging a survey, if necessary.

• Meet with your accountant and get your documents in order: Let your accountant know that you are in the market for a loan. He or she will need to make sure you have up-to-date financials, which include Profit & Loss statements and Balance Sheets. Your accountant should have filed your tax returns or extensions. In addition, you will have to identify all of the components of your business debt.

Be Ready for Site Visits:

• Put Your Best Foot Forward: If bank personnel or appraisers are coming to look at your business, understand your business plan and be able to explain how you will be profitable. GRP provides coaching to clients to help them understand the most important messages to relay to site visitors.

• Clean House: If you are looking to refinance an existing business, the property should be in decent shape with minimal deferred maintenance, if possible. If you are planning to renovate with the proceeds of the loan, you should be able to detail what will be improved and how much it will cost.

• Have a Plan for Obvious Problems: If the property is in need of obvious repairs (water damage, parking lot issues, etc.), be honest about those, be sure that you can explain the timeline and the financing of these planned improvements.

Be Ready to Borrow!

•  Clients who haven’t done their due diligence can experience frustration during the loan process. Not having a survey, an ESA or your own attorney can delay or even derail a loan closing.

• We will help guide you in the loan process. But we hope these ideas will help you before you even call us. When you have done your due diligence, you really are ready to borrow!

One of our chief responsibilities is advocating for borrowers. Even in the recent economic uncertain times, we have continued to advocate for our clients, and successfully closed loans.

Our Great Opportunities series discusses various aspects of the changing economic climate. There are still opportunities to secure funding for specific business plans. Read more about other aspects of finding funding in today’s climate here:

Becoming a Better Borrower

What Businesses do Lenders Like Now?

Choosing the Right Loan

Are you choosing the right loan right now?  If you are ready to secure funding for your business, you know there are many types of loans in the marketplace. What’s the best method for choosing the right loan, the one that most closely matches your business needs?

Choosing the Right Loan for You:

• What is the Purpose of Your Loan? Are you purchasing a new business or property? Refinancing? Constructing a new property? Buying out a partner? Renovating or converting a property? You can utilize different loans for different purposes; they are not interchangeable.

• How long do you want to need to pay back this loan?  How long do you intend to keep this property? How long will you need funding for? The longer the loan, the smaller your monthly payments. However, you will also have debt on your books for longer, which can affect future borrowing. Sometimes, there is a business opportunity that requires immediate action, which would necessitate using a loan that can close quickly.

• How much cash on hand do you have to fund this project? With the exception of refinances, most loans require an equity injection. Figure out exactly how much you are willing and able to contribute, along with your partners.

Types of Loans:

• Conventional Loans:  Conventional loans are traditional mortgages. These loans are secured by a first lien position on the real estate or business. This means that the collateral of the real estate and business “guarantee” the loan, along with any necessary personal guarantees of the borrower. Banks, credit unions and other financial institutions offer a variety of conventional loans.

•  SBA (Small Business Administration) loans: SBA loans can be used for a variety of financing needs associated with being a small business owner, including purchasing a business, refinancing an existing mortgage and expanding and renovating existing businesses. Their rates tend to be competitive. GRP Capital partners with a number of preferred lender partners (PLP) of the SBA in order to streamline the process of closing these loans.

• Bridge Loans: Bridge loans serve as a short-term solution when borrowers needs immediate funds. Bridge loans allow a borrower to make quick and strategic business decisions, without having to worry about securing long term financing and waiting for those loans to close.  This solution allows a client time to then secure permanent funding down the road. GRP Capital can help secure quick turnaround bridge loans. We also have access to our GRP Capital Debt Fund. We are proud of our reputation of being reliable, flexible and fair in utilizing this debt fund.

• USDA Business and Industry Guaranteed Loans (USDA B&I): These specialized loans are designed for projects in agricultural and rural settings. These loans support local employment and economic health in rural communities.

If you are considering a loan for purchase or refinance and would like to discuss choosing the right loan for you, feel free to contact our team.  

Wallet for personal financial statement blog

How to Fill out a Personal Financial Statement (PFS)

Lenders typically request that borrowers fill out a personal financial statement (PFS) when applying for a loan. This personal financial statement can vary somewhat, although the SBA uses Form 413. A PFS shows the bank a borrower’s cash position, how much liquidity they have to take on a new loan and their ability to pay back future loans. It’s important to understand the typical questions on a PFS, so you can fill them out accurately. Below are components of a PFS that are most confusing to our clients.

The Asset Portion of the PFS:

• What is Cash on Hand? Cash on hand is money that you have in checking and savings accounts and in cash on your person that is immediately available to you (liquid). Be prepared to furnish bank statements to support your cash availability. This is different from stocks and bonds, IRA’s or even Bitcoin.

• What do I need to know about my life insurance policies? You only need to declare life insurance policies if you have a whole life policy with a cash surrender value. So if you have a term life policy, you cannot consider it as a current asset, as it has no cash value.

• Real Estate and Automobiles as Assets:  Estimate the value of the automobiles you have and any real estate you own. This real estate includes your residences (primary and vacation homes). In addition, you will need to calculate the value of any commercial real estate you own. If you are a partner in a business that owns real estate, you can only claim the value of the real estate equal to the percentage of the business you own.

Declaring Liabilities on a PFS:

• Notes Payable and Installment Accounts:  Gather all of your personal loan and credit card statements to fill out the liabilities section of the PFS. You’ll need to know what your payments and balances are.

• Car Loans and Mortgage Loans: Your automobiles and real estate are assets, but if you owe money on them, they are also liabilities. Complete your PFS by stating what the payments and balances are, the interest rate, and in the case of mortgages, who the lender is and when the mortgage will be paid off. If your commercial real estate is for a business in which you are a partner, you only need to declare the percentage of the mortgage equal to your ownership percentage.

• Loans Against Life Insurance: Again, this is only applicable if you have a whole life policy (not a term policy) and you have taken out a loan against the cash value of the policy. Otherwise, this should be left blank.

• Unpaid Taxes: Most lenders would prefer that you pay off overdue taxes. But you can show a small amount on your PFS and work through that process prior to closing.

Net Worth:

Net worth is an equation. If you add up all your assets, and subtract all your liabilities, that is your net worth. It does not include your salary or your earning potential, just your declarable assets and liabilities.

We work closely with our clients to make sure the PFS is accurate. If you are considering a loan for purchase or refinance and would like to discuss your plans, feel free to contact our team. We will get to know you and your business objectives. Then we will recommend the best loans for you to consider. Initial consultations are free.   

FAQ’s for PFS (Frequently Asked Questions about Personal Financial Statements)

Lenders typically request that borrowers fill out personal financial statements (PFS) when applying for a loan. These personal financial statements can vary somewhat, although the SBA uses Form 413. A PFS shows the bank a borrower’s cash position, how much liquidity they have to take on a new loan and their ability to pay back future loans. It’s important to understand the typical questions on a PFS, so you can fill them out accurately. Below are components of a PFS that are most confusing to our clients.

The Asset Portion of Personal Financial Statements:

• What is Cash on Hand? Cash on hand is money that you have in checking accounts and in cash on your person that is immediately available to you (liquid). Be prepared to furnish bank statements to support your cash availability.

• What do I need to know about my life insurance policies? You only need to declare life insurance policies if you have a whole life policy with a cash surrender value. So if you have a term life policy, you cannot consider it as a current asset, as it has no cash value.

• Real Estate and Automobiles as Assets:  Estimate the value of the automobiles you have and any real estate you own. This real estate includes your residences (primary and vacation homes). In addition, you will need to calculate the value of any commercial real estate you own. If you are a partner in a business that owns real estate, you can only claim the value of the real estate equal to the percentage of the business you own.

Declaring Liabilities on a PFS:

• Notes Payable and Installment Accounts:  Gather all of your personal loan and credit card statements to fill out the liabilities section of the PFS. You’ll need to know what your payments and balances are.

• Car Loans and Mortgage Loans: Your automobiles and real estate are assets, but if you owe money on them, they are also liabilities. Complete your PFS by stating what the payments and balances are, the interest rate, and in the case of mortgages, who the lender is and when the mortgage will be paid off. If your commercial real estate is for a business in which you are a partner, you only need to declare the percentage of the mortgage equal to your ownership percentage.

• Loans Against Life Insurance: Again, this is only applicable if you have a whole life policy (not a term policy) and you have taken out a loan against the cash value of the policy. Otherwise, this should be left blank.

• Unpaid Taxes: Most lenders would prefer that you pay off overdue taxes. But you can show a small amount on your PFS and work through that process prior to closing.

Net Worth:

Net worth is an equation. If you add up all your assets, and subtract all your liabilities, that is your net worth. It does not include your salary or your earning potential, just your declarable assets and liabilities.

If you are considering a loan for purchase or refinance and would like to discuss your plans, feel free to contact our team.  

Setting 2022 Goals and Making Resolutions

It’s time to start setting your 2022 goals. Do you typically make New Year’s Resolutions? Even if you don’t, every good entrepreneur needs to set goals for the future.

Why Should You Make 2022 Goals?

Successful entrepreneurs realize that setting goals allows them the time to do three important things: reflect, brainstorm and develop an action plan. Failing to do each of these steps can lead to stagnant businesses. Worse, a failure to dream and plan adversely impacts you, the business owner. Doing things the same way over and over can allow you to become complacent and for your product to suffer. Customers notice. Your team notices, too.

Rick Patel, President of GRP Capital remarks, “Particularly now, having experienced the ups and downs of the past two years, we realize that setting 2022 goals is a must.”

Steps to Setting Your 2022 Resolutions:

• Reflect: How was your 2021? Take a look at your Profit & Loss report and compare it to 2019 (a more normal year as well as 2020. Are your revenues steady or increasing? If not, why not? Are your expenses stable or are there line items that are creeping up? How are you faring compared to your nearest competitors? What were your successes and your missteps this past year?

• Brainstorm: If money were no object, how would you grow or improve your business? Of course, money does matter. So which of these visions are worth pursuing, including finding funding?

• Action! Make a list of what can be improved this year. These improvements can be revenue enhancers or cost savers, they can be new products, new ideas, new marketing ventures, new hires, realignment and new funding. Write out everything you would like to eventually accomplish. Now, prioritize your list. Next to each action item, write the cost (if any) and the timeline.

• Funding Needs?  Are there worthwhile projects or ideas that only need funding in order to happen? If so, how much money will you need?

Krishan Patel, Managing Director of GRP Capital encourages clients to work with us as they reflect on the past year and determine future needs. “I would like all our colleagues clients to take the time to reflect and create a detailed business plan going forward. It’s good business practice. And if there is a need for future funding, I hope we can be of service.”

Our GRP Capital team specializes in finding the right lender for each project. We save our clients time and money, as we research  the best choices for their funding sources. Our experience allows our clients to find funding that is project-appropriate and will allow for sufficient cash flow. If you are considering becoming a first-time (or second or third time!) buyer, we can assist you.

Reset those New Year’s Business Resolutions – Increase Your Profits!

Did you set goals for 2019? Did you make promises to eat healthier, exercise regularly and be kinder to your mother-in-law? How are those resolutions holding up?

It is equally important for entrepreneurs to set achievable business goals—ones that will help your enterprises become more profitable.

At GRP Capital, we want all of our clients’ businesses to grow and prosper. We also know that growth doesn’t just happen. Growth occurs when owners and managers brainstorm the best ways to bring in more revenue, operate more efficiently and expand intelligently.

Some of our most successful clients have used the following methods to create growth, which has also improved their work life and contributed to greater personal wealth.

Property Improvement and Renovation:

Be honest about your property, whether it’s a hotel, assisted living facility, restaurant, office building, retail space, school or storage facility. How does it look to a new guest or visitor? More importantly, are there remodeling projects that would bring in revenue? Could you expand a lobby to include a fuller meal service? Would the cost of adding an elevator be offset by convention rentals?

Does your business have a season? For many businesses, summer drums up more business. Therefore, making decisions about renovation in the winter is an excellent idea as you can begin the construction right away and plan to be done by summer.

Financing Changes:

How is your current business financed, if at all? Often, you can benefit from the advice of our GRP advisors who will consult with you on the best types of financing for your goals. They can assist you in finding a loan that is a better fit or they can create a loan package that will allow for expenses and working capital so you can generate more growth.

This might be the time to contemplate switching types of loans. Consider changing from an SBA loan to a conventional loan or examine whether a non-recourse loan would be a good fit for your business plan. A bridge loan might be a great option when short-term financing is needed.

Brand New Project:

If you have proven yourself as an entrepreneur and manager, you can capitalize on your experience and equity to expand your reach into another similar project. You can also branch out into an “adjacent” business, one that utilizes your skills and knowledge, that allows you to experience new challenges and create new growth. We can help you evaluate market trends in various fields and help you assess the risks and rewards for traversing a new business path.

Franchise Changes:

In the hospitality world, clients often find that certain franchise affiliations offer greater opportunities for increased profits either because of corporate support, brand reputation or proximity and competition issues. There are times when “reflagging” a property is an excellent idea, especially if the costs can be quickly made up with increased occupancy and daily revenues.

Marketing Matters:

What were the ways that people found you and your business? What was the best use of your marketing dollars and what should you change in 2019? During winter is a great time to go over all of your financials from 2018. The numbers are a better indicator than just your gut feeling. When were you truly the most profitable? Why? Can you capitalize on these drivers?

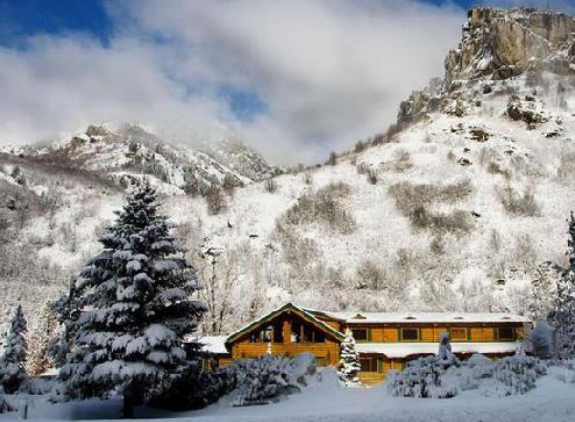
The Alaskan Inn – Ogden, Utah

Alaskan Inn

GRP recently arranged the financing for the purchase and renovation of the Alaskan Inn in Ogden, Utah.

Our client was an experienced builder, both of custom homes as well as office and retail space. He had a vision of what type of remodeling this boutique inn could benefit from. He was ready to try his hand at hotel ownership, utilizing the excellent management team that was already in place combined with his skills and knowledge regarding property improvement.

The Alaskan Inn is located near several ski resorts but was not currently marketing its proximity to the local ski scene. Also, this boutique bed and breakfast had previously been marketed as a couples’ retreat which limited family travelers, reunions and other groups from considering the locale during vacations and travel.

We were able to match our client with a Small Business loan product which provided him with competitive rates, funding for his property improvement and financing to purchase the property.

Our client took possession and immediately began renovations, reconfiguring the guest units so that whole families could occupy each guest dwelling. In addition, he made plans to put the property on the shuttle route for one of the local ski resorts so that clients could easily get to the gorgeous slopes nearby.

The Alaskan Inn already has devoted regular guests who love its breathtaking views and its unique setting. With skilled management and an eye for design, our client is sure his new property will continue to bring great joy to its guests. Our client was thrilled that, just before the renovation, Hallmark featured the property in their Christmas special, “Christmas Made to Order.”


Whether you are expanding your existing portfolio or investing in your first business, GRP Capital has the resources to help you meet your required capital needs. Our services include divisions of Real Estate Capital Markets, Small Business Financing, Construction Lending, GRP Capital Debt Fund, and Consulting and Advisory. Learn more at grpcapital.com.

We are a leader in commercial lending, advising, and investing because we are experienced, connected, and invested. Contact us to start the conversation.