Category Archives: Small Business

Louisiana Hotel Loan Closes

Our client needed a Louisiana hotel loan. He already owned a nearby property and knew the area well. He had been watching this particular hotel, as he perceived that it was underperforming in the market.

GRP Capital was ready to help.

But, because it’s Louisiana, sometimes Mother Nature has her own ideas. In this case, we were processing the loan during traditional hurricane season. Of course, a hurricane swept through the town, but did not damage the subject property. However, it did delay the appraiser being able to get out to the site.

Our client was solid as a rock, however. He understood that you have to be organized and calm during the storms in order to accomplish your goals.

GRP Capital Managing Director Krishan Patel commented, “We were so pleased with our client. He was organized and cheerful. He kept his eye on the prize, getting us documents quickly, discussing loan strategy with us and making necessary changes. It’s hard to be a business owner in the Bayou, but we were excited to close this Louisiana hotel loan.”  

How to Get Organized for a Future Loan: 

• Gather your tax documents: Make sure you have three years of business and personal taxes, including your W-2’s. Get them electronically from your accountant, to make them easy to submit.

•  Meet with your accountant: Tell your accountant that you will be applying for a loan. You will need updated financials and you may need to understand the details of your taxes. Be sure that the taxes you have match the official ones that were submitted. Apply for an extension if it’s time.

•  Tell Us Your Goals:  GRP Capital want to understand why you need financing. What are your business goals? What will you be using the money for? Why do you think this is the right time to make this decision?

Our GRP Capital team specializes in finding the right lender for each project. We save our clients time and money, as we research  the best choices for their funding sources. Our experience allows our clients to find funding that is project-appropriate and will allow for sufficient cash flow. If you are considering becoming a first-time (or second or third time!) buyer, we can assist you.
Georgia Liquor Store Purchase

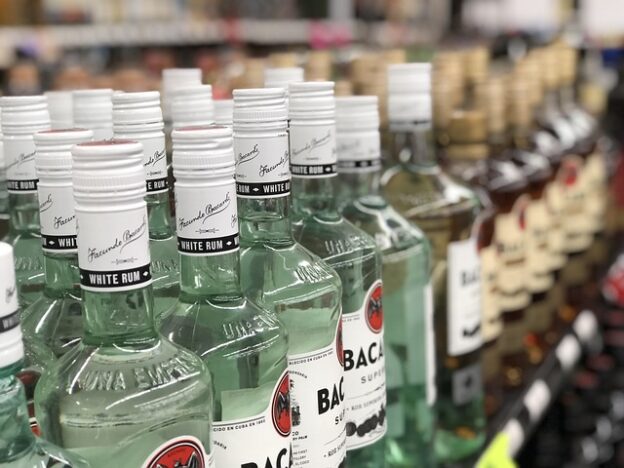
Lenders continue to show interest in funding a liquor store purchase. The liquor store industry, which is relatively pandemic-proof, stands out, even to the choosiest of lenders.

GRP Capital was very happy to close this liquor store purchase in Georgia. We knew the property well, having helped the seller, when he purchased this business several years ago. The seller was now ready to move on to other projects. We worked with both the seller and the buyers, our newest clients, to facilitate a smooth transition towards ownership. In addition, we collaborated with all of the parties to secure appropriate funding.

GRP Capital President Rick Patel noted, “We have a deep understanding of this business. As a result, I feel confident that the store is in good shape to continue to bring profits to the newest owner. I am personally proud that we have developed a history and reputation so that buyers, when they sell, recommend our services. We really loved getting to know the new buyers and consider them valued clients now, too.”

Why is a Liquor Store Purchase A Great Opportunity? 

Pandemic-proof: One thing we have learned is that we don’t know what curveball is coming next with COVID-19. Liquor stores however, seem to be relatively pandemic-proof. When bar and restaurant traffic diminishes, liquor stores’ sales remain constant and may even increase.  A successful liquor store should continue to be profitable, even if case numbers periodically increase. 

Adaptable: Liquor stores have built in systems for security that can be used to restrict touching of merchandise. A skilled manager can capitalize on liquor store offerings. Perhaps the store can expand into packaged treats, gift baskets or other items that are not easily available.

No Price Wars: Many local and state governments regulate liquor stores, forbidding discounts. This preserves minimum price structures. As a result,  a successful liquor store thrives because of its inventory and its service, not by trying to beat their competitors’ prices.

Our GRP Capital team specializes in finding the right lender for each project. We save our clients time and money, as we research  the best choices for their funding sources. Our experience allows our clients to find funding that is project-appropriate and will allow for sufficient cash flow. If you are considering becoming a first-time (or second or third time!) buyer, we can assist you.
Setting 2022 Goals and Making Resolutions

It’s time to start setting your 2022 goals. Do you typically make New Year’s Resolutions? Even if you don’t, every good entrepreneur needs to set goals for the future.

Why Should You Make 2022 Goals?

Successful entrepreneurs realize that setting goals allows them the time to do three important things: reflect, brainstorm and develop an action plan. Failing to do each of these steps can lead to stagnant businesses. Worse, a failure to dream and plan adversely impacts you, the business owner. Doing things the same way over and over can allow you to become complacent and for your product to suffer. Customers notice. Your team notices, too.

Rick Patel, President of GRP Capital remarks, “Particularly now, having experienced the ups and downs of the past two years, we realize that setting 2022 goals is a must.”

Steps to Setting Your 2022 Resolutions:

• Reflect: How was your 2021? Take a look at your Profit & Loss report and compare it to 2019 (a more normal year as well as 2020. Are your revenues steady or increasing? If not, why not? Are your expenses stable or are there line items that are creeping up? How are you faring compared to your nearest competitors? What were your successes and your missteps this past year?

Brainstorm: If money were no object, how would you grow or improve your business? Of course, money does matter. So which of these visions are worth pursuing, including finding funding?

Action! Make a list of what can be improved this year. These improvements can be revenue enhancers or cost savers, they can be new products, new ideas, new marketing ventures, new hires, realignment and new funding. Write out everything you would like to eventually accomplish. Now, prioritize your list. Next to each action item, write the cost (if any) and the timeline.

Funding Needs?  Are there worthwhile projects or ideas that only need funding in order to happen? If so, how much money will you need?

Krishan Patel, Managing Director of GRP Capital encourages clients to work with us as they reflect on the past year and determine future needs. “I would like all our colleagues clients to take the time to reflect and create a detailed business plan going forward. It’s good business practice. And if there is a need for future funding, I hope we can be of service.”

Our GRP Capital team specializes in finding the right lender for each project. We save our clients time and money, as we research  the best choices for their funding sources. Our experience allows our clients to find funding that is project-appropriate and will allow for sufficient cash flow. If you are considering becoming a first-time (or second or third time!) buyer, we can assist you.
Strong Management Results in New Refinance

GRP Capital is pleased to close another hotel refinance loan.

Our Southern California clients faced serious challenges during the beginning of the COVID-19 pandemic. Their hotel is located very close to Coachella. As a result, the cancellation of the famous festival in the early days of the pandemic could have been devastating. But our clients worked hard and kept their operating costs down. They continued to market their hotel carefully and when travel restrictions eased, were back in business.

Smart management eventually paid off. They also took advantage of the Small Business Administration stimulus package. Specifically, they obtained a modest EIDL (Economic Injury Disaster Loan) and two small rounds of Paycheck Protection Program loans. They used the proceeds from the loans appropriately, keeping their debt manageable. Their sound practices demonstrated that they were appropriate for a new refinance.

New refinance requirements when you have SBA COVID-19 loans:

• Subordinate the EIDL: At times, a lender will request a subordination. This means that the client gives permission to pay their new loan first and the EIDL  loan moves into second position. GRP Capital works with lenders who understand how to subordinate the loans, making the process seamless for our clients.

•  Apply for forgiveness of PPP loans: If PPP loans have been used appropriately (for payroll, mortgage and other pre-approved costs), borrowers can have the loan amounts forgiven. This process originates with the lender.

After working together as a team with Business Associate Vijal Suthar,  our clients now have a reasonable mortgage payment that makes their cash flow even stronger. They are renting rooms and eagerly awaiting the return of Coachella. Vijal Suthar said that “closing this refinance was a signal that lenders want to loan money. In particular, lenders prefer strong borrowers who show savvy business sense and strong management skills. These clients did the right things to keep their hotel afloat. I was very pleased that their reward was a very competitive and affordable loan.”

Are You Ready for a New Purchase or Refinance Loan?

Our GRP Capital team specializes in finding the right lender for each project. We save our clients time and money, as we research the best choices for their funding sources. Our experience allows our clients to find funding that is project-appropriate and will allow for sufficient cash flow. If you are considering becoming a first-time (or second or third time!) buyer, we can assist you.
Want to know more about other business opportunities? 

GRP Capital Closes Light Industrial Loan

GRP Capital closed a light industrial loan for our client recently. Our clients were star tenants in the building they were renting. As a result, they were ready to purchase their headquarters. GRP Capital worked in tandem with the clients and facilitated a closing for this light industrial facility.

GRP Capital Managing Director Krishan Patel upon closing this loan stated, “I was pleased to close this loan for our clients. They are very strong entrepreneurs and wanted the stability of owning their light industrial headquarters. We were even able to close the loan in time to obtain the benefits of the SBA stimulus package. As a result, our clients will have stable and affordable payments. We love focusing on the financing, so our clients can focus on running their business.” 

Like every commercial loan, this loan required an Environmental Site Assessment (ESA) and even a Phase II evaluation. Krishan Patel worked closely with our clients, along with our processing team. We scheduled the various site visits and obtained the needed documents. Thus, the ESA engineers could efficiently prepare their  reports for the lender’s approval. It is not unusual for light industrial sites to require more than just an ESA Phase I. It was important to make sure we communicated clearly with the clients, the lender and the ESA engineers.   

Things to Know about an Environmental Site Assessment: 

• ESA Phase I: Every full-time lender requires a Phase I for commercial loans, regardless of industry. This involves a visit to your business from an ESA engineer. The engineer will ask questions about the use of your building, its various plumbing and energy sources as well as waste management.

• ESA Inspection:  The ESA engineer will inspect major infrastructures of your location and will also take a quick look around at the public part of your business. These would include a dining room, factory floor, break rooms, sales offices, lobby, hotel guest rooms, etc.

•  But I never had an ESA before!: Sometimes, borrowers have received non-traditional financing like family loans, community loans and seller notes. These lenders may not have required ESA evaluations. This is common, but it is not the best business practice. Client borrowers should know what, if any, environmental conditions exist on their property.

• Light industrial and heavy manufacturing environmental concerns: Even hotels and restaurants require ESA evaluation and there are sometimes issues that need resolution. But the ESA is a critical component of the loan approval process for the manufacturing sector. This is because the manufacturing process can often contribute to environmental concerns.

•  After the ESA Phase I: After a Phase I, the engineer will either state that there are no environmental concerns or that there are. If there are concerns, the engineer will recommend a Phase II.

•  ESA Phase II: This will require another visit and typically more extensive studying, like collecting soil samples. After the Phase II work is completed, the engineer will issue the Phase II report. This report will also either state that there are concerns or give a list of recommendations. If there are recommendations, the lender and the client will seek assistance on figuring out how to remove any areas of concern.

Our GRP Capital team specializes in finding the right lender for each project. We save our clients time and money, as we research  the best choices for their funding sources. Our experience allows our clients to find funding that is project-appropriate and will allow for sufficient cash flow. If you are considering becoming a first-time (or second or third time!) buyer, we can assist you.
First Time Buyer Purchases Hotel

GRP Capital is pleased to announce the loan closing for our client, a first time buyer.  GRP Capital Managing Director Krishan Patel as well as GRP Capital President Rick Patel worked closely with our client and our lender to help everybody through this new terrain.  

Challenges for a First Time Buyer: 

• Finding the right property to purchase: First time buyers need to be picky. They should choose a property with profit potential. Even more importantly, a first time buyer needs to select a property that they can manage. Being too ambitious in terms of size of property, any issues facing the business or even complexity of management are not “perfect first time properties”.

•  Proving themselves to the lender:  Lenders want first-time buyers tho prove two things: financial stability and management experience. We worked in tandem with our lender and our clients, so that our clients could demonstrate their solid business plans. Our clients had experience but not decades of it. Our lender needed encouragement. Therefore, our relationship with the lender allowed them to trust us and our evaluation of the client’s skill set.

•  Solid Management Practices:  Lenders regularly request a management resume from potential borrowers. They are looking for years of experience and what type of businesses our clients have managed. We help our clients craft these resumes, so they can highlight their strengths during the underwriting process.

Rick Patel upon closing this loan stated, “We really wanted to help our client pursue their ownership dreams. They have good, strong management experience and will be able to improve the profit margins of this hotel. They are already executing their management plans as we approach the Florida high season.” 

Our GRP Capital team specializes in finding the right lender for each project. We save our clients time and money, as we research  the best choices for their funding sources. Our experience allows our clients to find funding that is project-appropriate and will allow for sufficient cash flow. If you are considering becoming a first-time (or second or third time!) buyer, we can assist you.
Independent Hotel Refinance

Our clients, owners of an independent hotel in western Florida, closed their loan. They previously had a private loan, and were looking for more traditional financing.  GRP Capital President Rick Patel worked closely with our clients, who are very organized, hands-on small business owners. 

Independent Hotel Ownership: 

• Proving revenue and expenses: Independent hotel owners typically do not participate in the Smith Travel Research (STR) reporting. As a result, this third party report is not available to lenders and underwriters. Instead, we at GRP Capital provided other documents that demonstrate the health of the business. These can include financials (which can even be certified if necessary) as well as sales tax reports and business bank statements.

•  Strong Management Skills:  Our clients are very hands-on. They know their budget and their expenses and can rattle off figures without even going back to the books. That is invaluable during the appraisal and underwriting process, when we are painting a picture of how the hotel functions.

•  Solid Marketing Plans:  Independent hotel owners have the benefits of being their own bosses without the parameters that franchises set. However, they also do not have the marketing budget that franchises have. It’s important to demonstrate how independent hoteliers are retaining and improving market share. Solid marketing plans are written out, with goals and timelines.

Rick Patel upon closing this loan stated, “I really enjoyed working with these clients. I love seeing a hard-working couple who are really just in need of a little help to kick-start their business to the next level. They benefited from our connections with our lender network and were able to transition to permanent  financing.” 

Our GRP Capital team specializes in finding the right lender for each project. We save our clients time and money, as we research  the best choices for their funding sources. Our experience allows our clients to find funding that is project-appropriate and will allow for sufficient cash flow. If you are considering becoming a first-time (or second or third time!) buyer, we can assist you.
Texas hotel loan closes

Our GRP Capital client is the proud owner of an East Texas hotel. Our clients purchased the hotel with extra assistance from the team to take this loan across the finish line.

GRP Capital’s  Senior Associate Ryan Dumas and our entire team worked closely with the very capable clients. Our clients, experienced managers and owners, only needed a little bit of direction in order to undergo the vigorous SBA underwriting process. We helped with restructuring the borrowing entity, including designating appropriate personal and corporate guarantors. As a result, our clients could more easily source their equity injection in a way that pleased the bank and met with SBA approval.  

Upon closing the loan, Ryan Dumas stated, “I really respect these clients a great deal. They are experts in the Texas hotel business and reached out to us as experts in financing. We worked very diligently with them to set up the loan so that everybody was happy: the clients, the bank and the SBA.”

If you are thinking of obtaining a new loan, now is the time to get your paperwork together, so you can streamline the process from origination to closing.

Get Organized While You Look for a Loan:

• Make sure your taxes are up to date.  File your taxes or file your extensions. Lenders will require three years of tax returns, both personal and business. This includes affiliate businesses that you own 20% or more of (or which you manage).

Monthly Financials are a Must: Even if your CPA typically only provides quarterly financials, during the loan underwriting process you will need to provide monthly financials. And be prepared: your financials will be updated at least once during underwriting. Be sure your CPA understands what will be required. We are happy to conference call with any of your business professionals to explain the process and what will be needed.

• Show Us Your Plans. What are your dreams for your business that this loan will allow you to embark on? What is the current budget and your future budget? How do you plan to market in the future? If you are buying a new business, what will you do that will improve upon the previous ownership?

Be Careful with Your Money.  Lenders will need to see nice clean bank statements, both business and personal. So don’t spend large amounts of money or take in large amounts of money. Don’t take on new debt (new cars or houses, new credit cards) and please don’t check your credit. If you get into a situation (you’ve been in a car accident and don’t have a choice about buying a car), talk with us first about strategies to deal with the emergencies during the loan underwriting process.

Our GRP Capital team specializes in finding the right lender for each project. We save our clients time and money, as we research the best choices for their funding sources. Our experience allows our clients to find funding that is project-appropriate and will allow for sufficient cash flow. If you are considering becoming a first-time (or second or third time!) buyer, we can assist you.

Transitioning from Owner Financing to Traditional Financing

Many of our clients come to us seeking traditional financing. Some clients have loans that are owner financed or seller financed. These can be convenient loans, but can be a bit too personal; it can be difficult to owe money to friends and family. In addition, traditional financing offers greater stability, government guarantees and even lower rates.

The entire GRP Capital team worked together to close this Florida hotel. We assisted the client to access traditional financing.

However, transitioning to traditional financing does require a bit of effort.

Preparing for Traditional Financing: 

Take Care of Title:  Traditional lenders want to make sure there are no “clouds on title”. This means that the borrower will clearly own the property and nobody can make a claim to a portion of it. Especially if a prior loan took place without going through title, potential borrowers must address this. Find a reputable title agent and ask them to run a preliminary title report. If there are issues that need resolving, hire a real estate attorney and begin to address them.

Bolster the Appraised Value: The appraisal process is critical, especially for properties that were not recently officially appraised. Shail Madhav collaborated with our clients to prove the value of the company. They tweaked business plans and budgets and even worked together on what to say when the appraiser came to inspect the property. All of this paid off, as the clients could justify the value of their property, including the loan to value ratio and future debt coverage.

•  Show Your Finances: Banks require clear, well-structured financial statements. These statements should include both Profit & Loss statements as well as Balance Sheets. If you or your accountant have not been regularly producing these, now is the time to take action. Prepare financial statements for the current year and the previous one to two years. Make sure the balance sheets match up with any loan statements or debt that you have.

How our client benefited:

Upon closing the loan, GRP Capital President Rick Patel stated, “ We were very pleased to close this loan for our client. The new loan gave him a lower mortgage payment and improved his cash flow. He now has more secure financing with government guarantees. The previous financing didn’t include either title work or environmental assessment. As a result, we were anxious to take those on. Now our client has a clear title and a clear environmental assessment. These accomplishments also added to our sense of security. Finally, the loan closed in time for our clients to take advantage of the latest stimulus package.  

Our GRP Capital team specializes in finding the right lender for each project. We save our clients time and money, as we research  the best choices for their funding sources. Our experience allows our clients to find funding that is project-appropriate and will allow for sufficient cash flow. If you are considering becoming a first-time (or second or third time!) buyer, we can assist you.

Quick Closing Was Key for Central Florida Hotel

A quick closing was crucial to our clients. They had negotiated a purchase sale agreement (PSA) with the seller. This PSA stipulated a set time for closing. Any delays would require an additional fee to be paid to the seller. As a result, GRP Capital turned to our trusted lenders’ network. In our search, we emphasized the need for a quick closing. We already knew our clients well, as they were repeat customers. But the loan was still complicated with multiple partners, each with large business portfolios. It took a full court press from all of our GRP Capital team to achieve this fast closing.

GRP Capital President Rick Patel worked closely with the multiple partners and the lender to secure this complex, high value loan for our clients. Our clients now have a conventional loan with competitive rates. 

Keys to a Fast Closing: 

• Organized finances:  We had worked with the clients’ certified public accountant (CPA) before. As a result, we knew that he could obtain documents quickly. These included up-to-date financials for the borrowing entity and all of the partners’ affiliate businesses (if they owned 20% or more of them). We could not have achieved a quick closing without our partnership with the clients’ CPA. Disorganization can delay closings.

•  Motivated sellers: Some clients think that it is only the buyers that have to provide documents. That is not the case. Sellers also have to provide financials, including up to date business statistics. In addition, the underwriter requires independent confirmation of these documents, sometimes through sales tax receipts. If a business has a Small Business Administration Economic Injury Disaster Loan, the lender requires even more documents. Lenders typically request promissory notes and will require that EIDL’s be paid off at or before closing.

•  Organized Equity Injection:  GRP Capital worked with the partners to identify the best bank accounts to use for the equity injection. These accounts were “clean”, which means without large deposits from outside sources. Submitting equity information early in the underwriting process prevents delays.

Rick Patel remarked, “To be honest, this loan was a challenge. The clients had an abbreviated timeframe. But the combination of our long-term relationship with the clients and their professionals (lawyers and accountants) helped us achieve a quick close. Lots of communication and dedication to serving our clients were critical.”  

Our GRP Capital team specializes in finding the right lender for each project. We save our clients time and money, as we research  the best choices for their funding sources. Our experience allows our clients to find funding that is project-appropriate and will allow for sufficient cash flow. If you are considering becoming a first-time (or second or third time!) buyer, we can assist you.